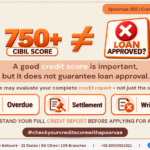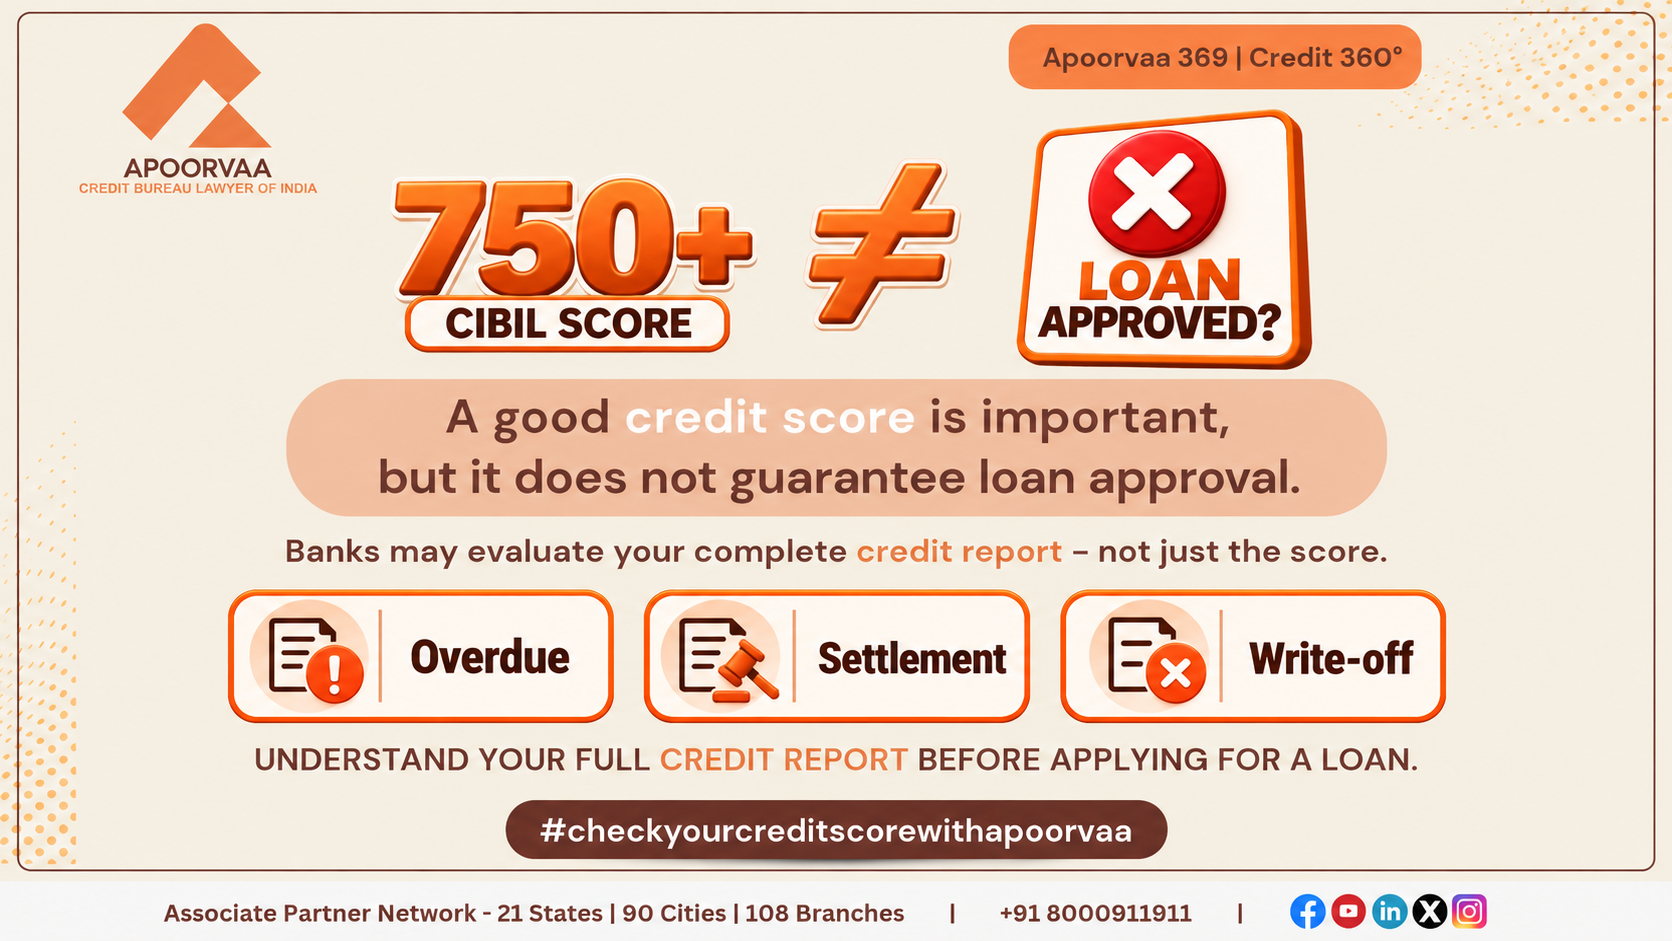
A 750 CIBIL Score is generally a positive indicator when applying for credit. But a customer can have a score of 750, 780 or even higher and still face loan rejection.
This often creates the assumption:
“My CIBIL Score is good. If the bank rejected my loan, there must be an error in my Credit Report.”
That conclusion is not always correct.
A Credit Score is an important component of credit assessment, but a lender can evaluate much more than the three-digit number.
The customer’s complete Credit Report, repayment behaviour, existing liabilities, credit exposure, income and repayment capacity, along with the lender’s own eligibility and underwriting criteria, may influence the final decision.
TransUnion CIBIL itself makes an important distinction: a score of 750 or above can put an applicant in a stronger position for credit consideration, but it does not guarantee loan approval. The lending decision ultimately rests with the lender.
Therefore:
750+ CIBIL Score ≠ Guaranteed Loan Approval
Understanding this distinction is the first step before treating a rejected loan as a Credit Rectification problem.
CIBIL Score and CIBIL Report Are Not the Same Thing
Customers often focus almost entirely on their Credit Score.
They open the report, look at the number at the top and, if it is above 750, assume that the entire credit profile must be satisfactory.
But a CIBIL Score is a numerical summary derived from credit information.
The CIBIL Report provides the broader credit information behind that score.
It may contain details relating to:
- loan and credit-card accounts,
- current and historical balances,
- repayment history,
- account status,
- credit limits,
- lender enquiries,
- and other reported credit information.
This distinction matters because the lender may evaluate the credit history behind the score, rather than treating 750 as an automatic approval threshold.
A strong score can exist alongside information that a lender may still consider relevant.
Why Can a Loan Be Rejected With a Good CIBIL Score?
There is no single answer applicable to every customer.
Consider two applicants.
Both have a CIBIL Score of 770.
At first glance, their credit position may appear similar.
But Customer A may have a relatively straightforward credit profile with manageable existing obligations.
Customer B may have several active loans, high revolving-credit utilisation, recent borrowing, historical repayment issues or a settlement reflected in the report.
The score may be similar.
The underlying credit profile can be very different.
This is why professional assessment should not begin with:
“Your score is 770, so the bank should approve the loan.”
Instead, it should begin with:
“What does the complete credit and eligibility profile show?”
- Previous Overdues Can Still Be Relevant
A customer’s score can improve over time.
But an improved current score does not necessarily mean every historical credit event has become irrelevant.
Suppose a customer previously delayed an EMI or had an overdue amount on a credit facility.
The account may later have been regularised, and over time the customer’s Credit Score may improve.
When the customer sees 760 or 780, they may believe:
“The old repayment problem no longer matters because my score has recovered.”
That should not automatically be assumed.
Depending on the information appearing in the Credit Report and the lender’s underwriting criteria, historical repayment behaviour may still be considered.
Current score and historical repayment behaviour are two connected but different aspects of the credit profile.
- A Settlement May Matter Even After the Score Improves
A settlement is another important example.
A customer may have settled a credit facility in the past and subsequently rebuilt the Credit Score.
The customer then applies for a new loan with a score above 750.
Does the improved score automatically make the historical settlement irrelevant?
Not necessarily.
The lender may evaluate the complete Credit Report, including the account status and historical information available to it.
This does not mean every settlement automatically causes every future loan application to be rejected.
The lender makes the final decision according to its own policy and overall assessment.
But customers should understand:
A strong current score does not automatically erase the relevance of the credit history behind it.
- Write-Off and Other Account Statuses Can Require Attention
A similar principle applies where the Credit Report reflects a write-off or another adverse account status.
A customer may ask:
“If the write-off is old and my score is now above 750, why is the bank still concerned?”
Because a Credit Score and an account status communicate different information.
The score summarises aspects of the overall credit profile.
An account status provides information relating to a particular credit facility.
A lender can consider both.
It is therefore possible for a customer to have:
a relatively good current Credit Score
and at the same time:
historical account information that a lender considers relevant.
These two things are not contradictory.
- High Credit Utilization Can Matter
A customer may also maintain timely repayments while using a significant portion of available revolving credit.
For example, consider a person with multiple credit cards who regularly uses a very high percentage of the available limits.
Payments may still be made.
The score may still appear relatively strong.
But the customer’s overall dependence on available credit may form part of the broader risk picture.
This is why credit utilisation deserves attention even when the headline Credit Score appears satisfactory.
A good score should not be interpreted as meaning:
“I can use almost all my available credit and the lender will look only at the score.”
The broader credit position matters.
- Too Many Existing Loans Can Create a Different Problem
This is one of the clearest examples of why a strong Credit Score does not guarantee another loan.
Imagine a customer with:
- a housing loan,
- a vehicle loan,
- two personal loans,
- credit-card obligations,
- and another recently opened credit facility.
Suppose every EMI is being paid on time.
That positive repayment behaviour may support a good Credit Score.
But the new lender still needs to answer a different question:
Can this customer comfortably service another loan?
That is not purely a Credit Score question.
It involves the customer’s existing liabilities and repayment capacity.
This is an important distinction for Credit Rectification as well.
If the existing liabilities are accurately reported, the problem is not automatically something that can be “rectified” in the Credit Report.
- Several New Loans Can Change the Overall Credit Picture
A customer can also have a strong score while having taken several new loans or credit facilities within a relatively short period.
Those facilities may all be performing normally.
But a lender considering another application may evaluate the customer’s recent borrowing activity and total exposure.
Again, the issue is not:
“Is the score good?”
The issue is:
“What does the customer’s overall credit position look like after considering all existing and recently added obligations?”
A three-digit score cannot answer every underwriting question on its own.
- Multiple Loan Enquiries May Be Visible
Loan applications can also create lender enquiries in the Credit Report.
This becomes particularly relevant after a rejection.
A customer may apply to Bank A and get rejected.
They then immediately apply to Banks B, C, D and E, hoping that one of them will approve the loan.
But if those lenders access the customer’s Credit Report in connection with the applications, additional enquiries may become part of the credit history.
This is why repeatedly applying for loans without first understanding the original rejection can be an ineffective approach.
A rejection should trigger diagnosis—not automatically another series of applications.
- The Problem May Have Nothing to Do With CIBIL
This is one of the most important points for customers to understand.
Suppose:
- the Credit Score is strong,
- the Credit Report is broadly accurate,
- repayment history is satisfactory,
- and there is no material Credit Report inconsistency.
The loan may still be rejected.
Why?
Because lenders can have their own eligibility and underwriting requirements involving matters such as:
- income,
- repayment capacity,
- existing EMI burden,
- employment or business profile,
- loan amount,
- product-specific eligibility,
- internal risk policy,
- and other application parameters.
Therefore:
Loan Rejected ≠ Automatically CIBIL Problem
This distinction prevents customers from trying to “repair” a Credit Report when the actual reason lies elsewhere.
When Does a 750+ Loan Rejection Become a Credit Report Concern?
Now we come to the more important Credit Rectification question.
A good score with a rejected loan deserves closer Credit Report attention when there is reason to believe the underlying reported information itself may be inaccurate or inconsistent.
For example:
An Account You Don’t Recognise
A credit facility appears that the customer believes does not belong to them.
Potentially Incorrect Outstanding Balance
The balance reflected in the report appears materially inconsistent with the underlying facility.
Repayment History Concern
The reported repayment history appears inconsistent with the actual payment position.
Account Status Concern
The report reflects a status that appears inconsistent with the underlying credit facility.
Ownership or Other Material Information Concern
Important information appears to be attributed incorrectly or does not accurately represent the customer’s credit facility.
These situations are fundamentally different from simply having an old negative entry that is genuine.
Negative Credit Information Is Not Automatically an Error
This distinction is essential in responsible Credit Rectification.
Suppose a customer genuinely had an overdue.
Or genuinely entered into a settlement.
Or genuinely delayed repayments.
The customer may understandably dislike seeing that information in the Credit Report.
But:
Unfavourable information and inaccurate information are not the same thing.
A Credit Rectification assessment should therefore not begin with:
“Which negative entries can we remove?”
It should begin with:
“Is the information accurate?”
That single question separates genuine Credit Rectification from unrealistic promises about Credit Scores.
Why the Complete Credit Report Should Be Understood Before Applying
Today’s video carries a very important practical message:
Don’t wait for a rejection to understand your Credit Report.
Before an important loan application, customers often check only the score.
If it says 750+, they proceed.
A more complete approach is to understand the overall credit position.
That includes awareness of:
existing credit facilities
repayment history
outstanding liabilities
account statuses
credit utilisation
recent borrowing
credit enquiries
and whether the report contains any information that appears genuinely inaccurate.
The purpose is not to guarantee that the bank will approve the application.
The purpose is to understand what the lender may see before the application is evaluated.
The Apoorvaa Perspective: Diagnose Before You Rectify
At Apoorvaa – Credit Bureau Lawyer of India, a customer may approach us saying:
“My CIBIL Score is 780 but my loan was rejected. Please rectify my CIBIL.”
But the score alone does not tell us whether Credit Rectification is actually required.
The first distinction should be:
Is there a genuine Credit Report problem?
or
Is this a lender eligibility problem?
If inaccurate information is appearing in the Credit Report, that may require professional assessment.
But if the Credit Report is accurate and the customer does not meet the lender’s eligibility or repayment-capacity requirements, Credit Rectification is not the solution.
Identify the problem first. Then determine the appropriate response.
That is far more responsible than promising a higher score or guaranteed loan approval.
Credit Report Problem or Lender Eligibility Problem?
When a customer has a 750+ CIBIL Score but the loan is rejected, the first step should not be to assume that the CIBIL Report needs rectification.
There are two very different possibilities.
Credit Report Concern
There may be genuinely inaccurate or inconsistent information in the Credit Report—for example, incorrect account ownership, balance, repayment history or account status.
Lender Eligibility Concern
The Credit Report may be broadly accurate, but the customer may not satisfy the lender’s requirements relating to income, repayment capacity, existing liabilities, loan amount, product criteria or internal risk policy.
The distinction is important because:
Credit Rectification can address genuine Credit Report concerns. It cannot correct a lender’s eligibility decision when the underlying Credit Report is accurate.
What Should You Understand After a Loan Rejection?
A rejected loan application should trigger analysis before another application.
Instead of immediately approaching another bank, understand what may have influenced the first decision.
Was there an adverse account status in the Credit Report?
Were existing liabilities already high?
Was credit utilisation significant?
Were there several recent loans or enquiries?
Did the customer meet the lender’s income and repayment-capacity criteria?
Does any information in the Credit Report appear genuinely inaccurate?
Or was the application declined because of the lender’s own internal policy?
These questions help determine whether the customer is dealing with a credit-reporting problem or a credit-eligibility problem.
Why Applying to Multiple Banks After Rejection May Not Solve the Problem
A common reaction to rejection is:
“One bank rejected me, so I’ll apply to five more.”
But this does not address the reason for the original rejection.
When a lender accesses a CIBIL Report in connection with a credit application, the access may be recorded as an enquiry. CIBIL explains that frequent applications for new credit can affect the credit profile, and it recommends applying for new credit in moderation.
Therefore, submitting several applications without understanding the underlying issue may simply create additional enquiries while leaving the actual problem unresolved.
More applications are not a substitute for understanding the reason for rejection.
A Strong Score Does Not Mean Unlimited Borrowing Capacity
Consider a customer with a CIBIL Score of 780.
The customer has consistently paid existing obligations and therefore maintains a strong score.
But the same customer already has:
- a home loan,
- vehicle loan,
- personal loan,
- credit-card obligations,
- and another recently opened loan.
The customer now applies for another personal loan.
The bank may ask a question that the 780 score cannot answer on its own:
“Does this customer have sufficient repayment capacity for another EMI?”
This is why creditworthiness and borrowing capacity are related but not identical concepts.
A customer can have good repayment behaviour while simultaneously carrying substantial financial obligations.
If those liabilities are accurately reflected in the Credit Report, Credit Rectification is not intended to make genuine liabilities disappear merely to improve loan eligibility.
What If an Old Settlement Is Affecting the Application?
This requires careful handling.
A customer may have settled an account several years earlier and subsequently rebuilt the Credit Score above 750.
If the settlement is accurately reflected, its presence should not automatically be classified as a Credit Report error merely because a new lender considers it negatively.
Similarly, if a write-off, overdue or repayment delay genuinely occurred, the customer’s preference for its removal does not by itself make the information inaccurate.
However, the situation changes if the reported status itself does not accurately reflect the underlying account position.
That is why professional assessment should focus on the accuracy and context of the information rather than promising removal of every adverse entry.
What If the Customer Says, “But I Already Paid the Loan”?
This is another situation where the complete Credit Report matters.
Payment of a loan and the manner in which the account is ultimately reported are related issues, but simply saying “I have paid” does not provide enough information to determine whether the Credit Report is correct.
The account may need to be understood in terms of its actual history and the status being reported.
For example, the relevant question may be whether the information currently appearing accurately reflects the underlying credit facility and its reported position.
This is why Credit Rectification should be based on documented facts and actual reporting concerns, rather than assumptions based only on the current score.
What If the Credit Report Contains an Account You Never Took?
That is a fundamentally different situation.
Suppose a customer obtains the Credit Report and finds a credit facility that they genuinely do not recognise.
Or the report contains account ownership information that appears to belong to another person.
Now the issue is not simply:
“My loan was rejected despite a 750+ score.”
The issue may be:
“My Credit Report may contain information that does not belong to me.”
Potentially inaccurate ownership information deserves proper attention because it relates directly to the integrity of the customer’s credit profile.
This is the type of situation where a professional Credit Report assessment can become relevant.
What If the Outstanding Balance Appears Wrong?
A customer may also identify an outstanding balance that appears materially inconsistent with the underlying loan or credit facility.
Again, the objective should not be to change the number simply because a lower balance would look better.
The correct question is:
Does the reported balance accurately reflect the underlying credit position?
If yes, it is genuine credit information.
If there appears to be a genuine discrepancy, the matter may require assessment.
The same principle applies to repayment history, account status and ownership information.
Credit Rectification Should Start With the Root Cause
A loan rejection can create pressure.
The customer may urgently need finance and begin looking for someone who promises:
“CIBIL clear kar denge.”
“Negative entries remove kar denge.”
“Score 800+ kar denge.”
“Loan approve ho jayega.”
Such promises can create unrealistic expectations.
A professional Credit Rectification approach should instead identify the root cause.
If the Credit Report contains genuinely inaccurate information, understand that issue.
If the report contains genuine adverse history, do not misrepresent it as an error.
If the report is accurate and the rejection is caused by lender eligibility, acknowledge that Credit Rectification may not be the appropriate solution.
Correct diagnosis is more important than promising a quick score increase.
When Is Professional Credit Rectification Relevant?
Professional assessment becomes more relevant when there is a genuine concern regarding reported credit information.
Examples may include:
Account Ownership Concern
A credit facility appears that the customer does not recognise.
Outstanding Balance Concern
The reported amount appears materially inconsistent with the actual facility position.
Repayment History Concern
The repayment information appears inconsistent with the underlying account history.
Account Status Concern
The status appearing in the Credit Report does not appear to reflect the actual facility position.
Material Reporting Inconsistency
Important credit information appears inconsistent and requires examination.
The key word in every case is accuracy.
Credit Rectification should not be based simply on whether an entry is favourable or unfavourable.
What Credit Rectification Cannot Promise
Customers should also understand the limitations.
It Cannot Guarantee a Particular CIBIL Score
Even where genuinely inaccurate information is corrected, no responsible service should guarantee that the score will become 750, 800 or any other specific number.
It Cannot Guarantee Loan Approval
The lender still applies its own eligibility and underwriting criteria.
It Cannot Turn Genuine Credit History Into an Error
An accurately reported repayment delay, settlement, overdue or other historical event does not become inaccurate simply because it affects a future credit application.
It Cannot Solve Every Loan Rejection
If the real issue is insufficient income, excessive existing liabilities, repayment capacity or another lender-specific requirement, changing the Credit Report is not necessarily the solution.
This is why Apoorvaa’s approach must begin with understanding the nature of the customer’s problem.
Should You Check Only Your Score Before Applying?
No.
This is perhaps the most practical takeaway from today’s topic.
Before an important loan application, a customer may check the CIBIL Score and see:
780
The natural reaction is:
“Good. My credit is fine.”
But the score is only one part of the picture.
Understanding the complete Credit Report can help a customer become aware of:
- existing credit facilities,
- outstanding obligations,
- repayment history,
- account statuses,
- recent enquiries,
- and any information that appears unfamiliar or potentially inaccurate.
The objective is not to guarantee approval.
It is to understand the credit profile that may be evaluated as part of the lending process.
Frequently Asked Questions
My CIBIL Score is 750+. Why was my loan rejected?
A strong CIBIL Score does not guarantee approval. The lender may consider the complete Credit Report, repayment history, existing liabilities, repayment capacity, income, product eligibility and its internal underwriting policy.
Is 750 a guaranteed loan-approval score?
No. There is no universal score at which every lender must approve a loan.
Can an old overdue matter even if my score is now good?
Potentially, yes. Historical repayment information may still form part of the Credit Report and may be considered according to the lender’s assessment policy.
Can a settlement affect my loan application after my score improves?
It may be relevant to a lender’s overall assessment if the settlement is reflected in the Credit Report. Its presence does not automatically mean the report is inaccurate.
Can a write-off matter with a 750+ score?
Potentially. A Credit Score and an account status provide different information about the credit profile.
Can high credit utilisation matter even with a good score?
Yes. A strong score does not necessarily mean the customer’s existing use of credit or overall exposure will be irrelevant to a lender.
Should I apply to several banks if one rejects my loan?
It is better to first understand the possible reason for rejection. Multiple formal credit applications may generate additional lender enquiries.
Does loan rejection prove there is a CIBIL error?
No. A loan can be rejected even where the Credit Report is accurate.
When does Credit Rectification become relevant?
It becomes relevant where there is a genuine concern regarding the accuracy or reporting of credit information, rather than simply because the customer dislikes a negative but accurate entry.
Can Credit Rectification remove every settlement, write-off or overdue?
No such blanket promise should be made. Genuine credit history should not be treated as inaccurate merely because it is adverse.
Can Credit Rectification guarantee an 800+ CIBIL Score?
No.
Will correcting an inaccurate Credit Report guarantee loan approval?
No. The final lending decision remains subject to the lender’s own assessment.
The Apoorvaa Approach: Diagnose the Credit Problem Before Offering a Solution
At Apoorvaa – Credit Bureau Lawyer of India, the important question is not simply:
“What is your CIBIL Score?”
We need to understand:
“What is actually happening inside your Credit Report?”
A customer with a 720 score may have one type of concern.
Another customer with a 780 score may have an entirely different issue.
And a third customer with a 780 score and a rejected loan may have no Credit Report error at all—the rejection may arise from lender eligibility.
This is why Credit Rectification should not be reduced to chasing a higher number.
The objective is to identify genuine credit-reporting concerns and understand the root cause.
Final Takeaway
A 750+ CIBIL Score is an important positive indicator, but it is not a loan approval guarantee.
A lender may evaluate much more than the score, including the complete Credit Report, repayment history, existing liabilities, credit exposure, repayment capacity and its own eligibility criteria.
Therefore, if your loan is rejected despite a good score, don’t immediately assume:
“My CIBIL needs to be fixed.”
First determine:
Is there a genuine Credit Report problem—or is this a lender eligibility problem?
If the underlying Credit Report contains genuinely inaccurate information, professional Credit Rectification assessment may be appropriate.
If the Credit Report is accurate and the rejection results from eligibility or underwriting criteria, Credit Rectification should not be presented as the solution.
That distinction can save customers from repeated applications, unrealistic promises and unnecessary attempts to alter information that may already be correctly reported.
Professional Credit Report Assessment
If you have a 750+ CIBIL Score but your loan has been rejected, and you believe your Credit Report contains an inaccurate account, balance, repayment history, ownership or account status, the underlying information should be assessed before deciding whether Credit Rectification is required.
Apoorvaa – Credit Bureau Lawyer of India assists individuals and businesses with genuine Credit Report and Credit Rectification concerns.
📞 Free Credit Helpline: +91 8000 911 911
Credit Rectification does not guarantee a particular Credit Score, deletion of genuine credit history, loan eligibility or loan approval.
Related Credit Education