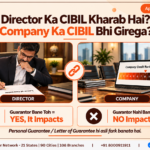
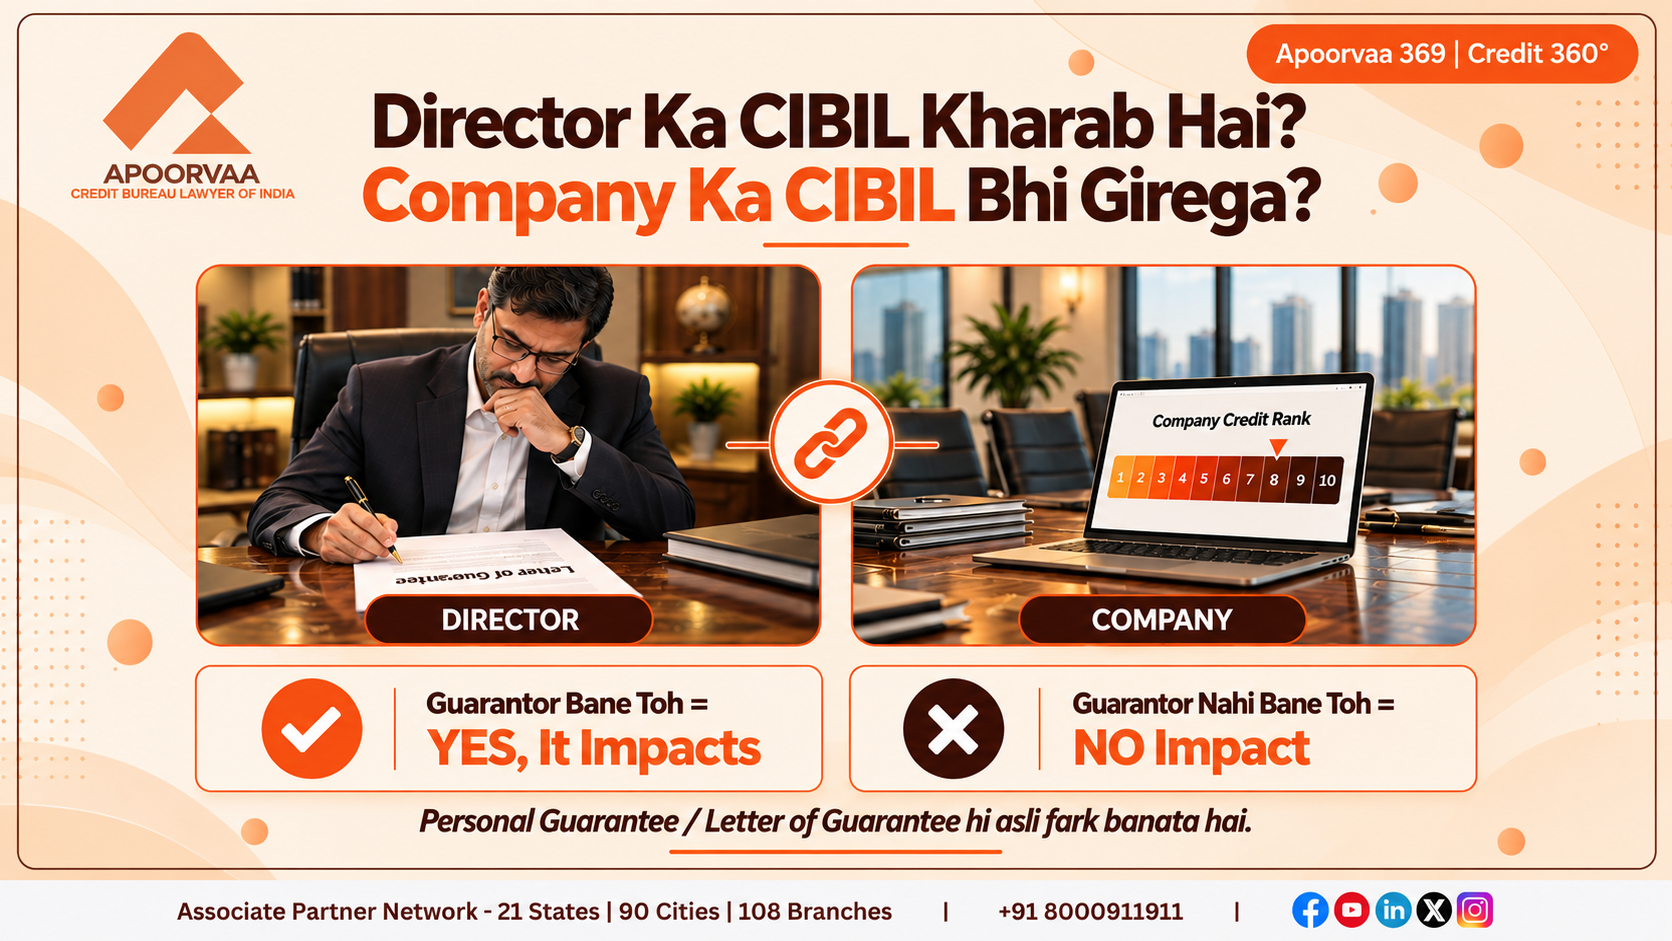
A director of a private limited company has a poor personal CIBIL Score due to missed EMIs, overdue loans or previous repayment difficulties.
Does this mean the company’s CIBIL Rank will also deteriorate?
Now consider the opposite situation.
A company has taken a business loan, and the bank has obtained personal guarantees from its directors. If the company defaults, will the directors’ individual CIBIL Reports also be affected?
These are important questions for company directors, MSME owners and business promoters because personal and corporate credit obligations can become connected through loan guarantees.
However, a director’s personal credit report and a company’s commercial credit report are not automatically linked simply because the individual holds a directorship.
The actual impact depends on who borrowed, who provided the guarantee, the nature of the obligation and how the lender reported the credit information.
Understanding these relationships is essential before assuming that a problem in one credit report will automatically affect the other.
- Understanding Director CIBIL and Company CIBIL
Before examining the impact of loan guarantees, it is important to understand the difference between an individual’s credit report and a company’s commercial credit report.
What Is a Director’s Personal CIBIL Report?
A director’s personal CIBIL Report contains information about the individual’s reported credit obligations.
Depending on the available information, it may include:
- Personal loans and other individual borrowings.
- Credit card accounts.
- Outstanding balances and overdue amounts.
- Repayment history.
- Relevant co-borrowing or guarantee obligations.
- Credit enquiries and account status.
An individual’s CIBIL Score is a personal credit-risk indicator based on the applicable scoring methodology and available credit information.
A director’s designation does not automatically make every company loan part of that individual’s personal borrowing history.
What Is a Company’s CIBIL Report?
A Company Credit Report, also called a Commercial Credit Report, contains information about the business entity’s reported credit facilities and borrowing behaviour.
It may include:
- Company identification details.
- Existing and historical commercial loans.
- Cash credit and overdraft facilities.
- Sanctioned limits and outstanding balances.
- Repayment history and overdue amounts.
- Adverse account classifications.
- Relevant reported guarantee exposures.
- CIBIL Rank, where applicable.
Eligible companies may receive a CIBIL Rank ranging from 1 to 10.
Rank 1 represents the lowest relative commercial credit risk, while Rank 10 represents the highest.
The company’s CIBIL Rank and a director’s personal CIBIL Score are different indicators. They should not be treated as interchangeable.
- Does a Director’s Poor Personal CIBIL Automatically Affect the Company?
Consider the following example.
A director of ABC Private Limited has taken a personal loan of ₹15 lakh.
Due to financial difficulties, the director misses several EMIs.
The missed repayments may appear in the director’s personal credit report.
Will ABC Private Limited’s commercial credit report automatically show the same default?
Generally, no.
If the company is not a borrower, guarantor or otherwise obligated in relation to that personal loan, the director’s repayment delay does not automatically become a company loan default.
The director’s personal credit history and the company’s commercial credit history remain separate for credit-reporting purposes.
Can the Director’s Poor CIBIL Still Affect a Company Loan Application?
Yes, it may.
Banks can examine the personal creditworthiness of promoters or directors while assessing a company’s business loan application.
For example, a lender may review the credit history of a principal promoter before sanctioning a substantial business loan.
If the promoter has significant personal repayment problems, the lender may consider those concerns in its overall credit appraisal.
However, this is different from an automatic deterioration in the company’s CIBIL Rank.
A lender considering the director’s personal credit history does not mean that the director’s personal loan has become a company borrowing obligation.
- What Happens If the Company Gives a Corporate Guarantee for a Director’s Loan?
The situation becomes different when a company provides a corporate guarantee for another borrower’s credit facility.
Suppose a director obtains a loan and ABC Private Limited provides a corporate guarantee.
The director is the principal borrower, while the company has undertaken a guarantee obligation under the relevant agreement.
If the director defaults, the lender may have rights against the corporate guarantor according to the guarantee terms and applicable law.
Can This Affect the Company’s Commercial Credit Report?
Potentially, yes.
A corporate guarantee can create credit exposure for the company.
Depending on the reporting arrangements, applicable requirements and information furnished by the lender, the guarantee exposure or related adverse information may become relevant to the company’s commercial credit profile.
However, the presence of a corporate guarantee does not automatically establish that every missed EMI will cause a particular reduction in the company’s CIBIL Rank.
The actual position requires examination of:
- The identity of the principal borrower.
- The corporate guarantee agreement.
- The obligations covered by the guarantee.
- The status of the underlying loan.
- The lender’s reported credit information.
- The company’s commercial credit report.
Why Is the Corporate Guarantee Agreement Important?
A director’s relationship with a company does not, by itself, establish that the company has guaranteed the director’s personal loan.
The guarantee must be supported by the relevant contractual and corporate arrangements.
This distinction is especially important when a company finds unfamiliar credit exposure or guarantee-related information in its commercial credit report.
The reported obligation should be verified before concluding that it is either accurate or incorrect.
- Can a Company Loan Default Affect Directors’ Personal CIBIL Reports?
Now consider the reverse situation.
ABC Private Limited obtains a business loan of ₹3 crore.
The bank also obtains personal guarantees from two directors.
Later, the company experiences financial difficulties and fails to meet its repayment obligations.
Can the directors’ personal credit reports be affected?
Yes, they may be affected because the directors have undertaken personal guarantee obligations.
Depending on the reporting arrangements and applicable credit-information requirements, the guaranteed borrowing and related adverse information may be reflected in the guarantors’ individual credit profiles.
What Is a Personal Guarantee?
A personal guarantee is an undertaking by an individual to meet specified obligations of another borrower if the borrower fails to perform, subject to the terms of the guarantee and applicable law.
For company finance, banks may require guarantees from promoters or directors.
However, not every director is automatically a guarantor, and guarantee requirements vary between lending arrangements.
Does Every Company EMI Bounce Automatically Reduce the Director’s CIBIL Score?
Not necessarily.
The existence of a personal guarantee creates a relevant obligation, but the actual credit-reporting impact depends on the reported account information and applicable arrangements.
It is not possible to predict a specific CIBIL Score reduction merely from the fact that a company has missed an EMI.
Similarly, a guarantee-related entry should not be assumed to be incorrect simply because the borrowing was taken in the company’s name.
The guarantee documents and reported information must be examined together.
- Personal Guarantee vs Corporate Guarantee: Key Differences
Personal and corporate guarantees can both connect one borrower’s obligations to another person or entity.
However, they are not the same.
| Particulars | Personal Guarantee | Corporate Guarantee |
| Guarantor | An individual | A company or corporate entity |
| Common business context | Director guarantees a company loan | Company guarantees another borrower’s facility |
| Nature of exposure | Individual guarantee obligation | Corporate guarantee obligation |
| Relevant credit profile | Individual credit information, where reported | Commercial credit information, where reported |
| Impact of default | Depends on guarantee terms and reporting | Depends on guarantee terms and reporting |
| Automatic score or rank reduction | Not established solely by the guarantee | Not established solely by the guarantee |
Why This Distinction Matters for MSMEs
MSME promoters frequently deal with multiple borrowing arrangements, including business term loans, working capital facilities and personal borrowings.
A director may be a borrower in one facility, a guarantor in another and have no personal obligation in a third.
Therefore, identifying the correct borrowing and guarantee relationship is essential when reviewing credit reports.
The same individual may have different legal and credit-reporting responsibilities across different facilities.
- What Happens If a Director Has Not Provided a Personal Guarantee?
Consider a private limited company with three directors.
The company obtains a business loan, but only two directors provide personal guarantees.
Later, the company defaults on its repayment obligations.
Will the third director’s personal CIBIL Report automatically be affected?
Not ordinarily.
Simply holding the position of director does not automatically make an individual a personal guarantor for every company borrowing.
If the third director has not provided a personal guarantee and has no other relevant personal obligation connected with the loan, the company’s default does not automatically become that director’s personal borrowing default.
However, the complete loan documentation must be examined before reaching a conclusion.
A director may have obligations under a separate agreement, co-borrowing arrangement or other legally relevant circumstances.
Therefore, the correct question is not simply whether someone is a director.
It is whether that individual has undertaken an obligation connected with the borrowing.
- Can a Director’s Poor Personal CIBIL Affect Company Loan Eligibility?
Yes. A director’s personal credit history may influence a lender’s assessment of a company loan application.
Banks may examine the creditworthiness of promoters, directors and proposed guarantors when evaluating business finance.
For example, a company may have a favourable CIBIL Rank and a profitable business, while its principal promoter has significant overdue personal loans.
The bank may consider the promoter’s credit history as part of its overall credit-risk assessment.
However, this does not mean the promoter’s personal default automatically reduces the company’s CIBIL Rank.
Two separate matters must be understood:
- Credit reporting: Whether a borrowing or guarantee obligation is correctly associated with the director or company.
- Loan appraisal: Whether the lender considers the director’s personal credit history when evaluating the company’s loan application.
A personal credit problem can influence a lending decision without automatically appearing as a default in the company’s commercial credit report.
- Practical Examples: Director CIBIL and Company CIBIL
The following examples illustrate how borrowing and guarantee relationships can differ.
| Situation | Possible credit-reporting implication |
| Director defaults on a personal loan; company has no related obligation | Personal credit report may be affected; no automatic company default |
| Director defaults on a loan guaranteed by the company | Corporate guarantee exposure may become relevant to the company’s commercial credit profile |
| Company defaults; director has given a personal guarantee | Director’s personal credit profile may be affected, depending on reporting |
| Company defaults; director has no personal obligation | No automatic personal borrowing default solely because of directorship |
| Director has poor personal CIBIL but company has a favourable rank | Lender may consider the director’s credit history without an automatic change in company rank |
These are illustrative situations. Actual reporting and lending outcomes depend on the underlying documents, account information and applicable requirements.
- Common Guarantee-Related Credit Reporting Discrepancies
When reviewing director and company credit reports, certain entries may require verification.
Examples include:
- A guarantee incorrectly associated with a director.
- An unfamiliar borrowing account appearing in a company’s commercial credit report.
- Incorrect outstanding or overdue amounts.
- A guarantee-related account reported with an inaccurate status.
- Incorrect identification of the borrower or guarantor.
- Information that does not match the relevant lender records.
However, an unfavourable guarantee-related entry is not automatically an error.
A valid guarantee may create a genuine financial obligation, even when the guarantor did not receive the loan proceeds.
Similarly, an accurately reported historical default cannot simply be deleted because it affects creditworthiness.
Company Credit Rectification and individual credit rectification should focus on verified reporting inaccuracies.
- Why Professional Analysis of Both Credit Reports Matters
When a company or director faces a guarantee-related credit concern, examining only one credit report may not provide the complete picture.
The relevant personal and commercial credit reports can contain different information because they relate to different borrowers and obligations.
Professional analysis can help identify the reported accounts, guarantee exposures and information requiring clarification.
It can also help distinguish genuine credit-risk concerns from possible reporting discrepancies.
However, professional analysis does not guarantee removal of accurate adverse information, improvement in CIBIL Score or CIBIL Rank, or approval of a business loan.
The objective is to understand the available credit information and determine whether a genuine reporting discrepancy requires attention.
Frequently Asked Questions
Does a director’s poor CIBIL automatically reduce the company’s CIBIL Rank?
No. A director’s personal CIBIL Score and a company’s commercial CIBIL Rank are separate indicators. A director’s personal default does not automatically become a company credit default.
Can a company’s loan default affect a director’s personal CIBIL?
Yes, particularly where the director has provided a personal guarantee and relevant information is reported by the lender.
Is every director automatically a guarantor for company loans?
No. The actual loan and guarantee documentation determines which directors have undertaken personal guarantee obligations.
Can a company guarantee a director’s personal loan?
A company may provide a corporate guarantee where legally permitted and appropriately authorised. Such arrangements require consideration of applicable company law, approvals and contractual requirements.
Can a bank reject a company loan because a director has poor CIBIL?
A lender may consider a director’s or promoter’s personal credit history as part of its credit assessment. The decision depends on the lender’s policies and the overall application.
Can an incorrectly reported guarantee be corrected?
Genuine reporting inaccuracies can be raised for verification through the concerned credit institution and applicable dispute-resolution process. Correction depends on the underlying records and verification outcome.
Conclusion
A director’s personal CIBIL Report and a company’s Commercial Credit Report are separate credit profiles.
However, personal and corporate guarantees can create important financial and credit-reporting connections between them.
A director’s poor personal CIBIL Score does not automatically reduce the company’s CIBIL Rank.
Similarly, a company’s loan default does not automatically make every director personally responsible for the borrowing.
The actual relationship depends on who borrowed, who guaranteed, the obligations undertaken and the information reported by the lender.
Before applying for additional finance or raising a credit-reporting dispute, it is important to understand these distinctions.
Professional Director and Company Credit Report Analysis — Apoorvaa
Is your company’s CIBIL Rank affected by adverse credit information?
Are you concerned about a director’s personal CIBIL Report or a guarantee-related credit-reporting issue?
Apoorvaa helps individuals and businesses understand their credit information and identify genuine reporting discrepancies that may require verification.
Get your personal and Company Credit Reports professionally analysed by Apoorvaa.
For information and guidance, contact our helpline.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Related Credit Education