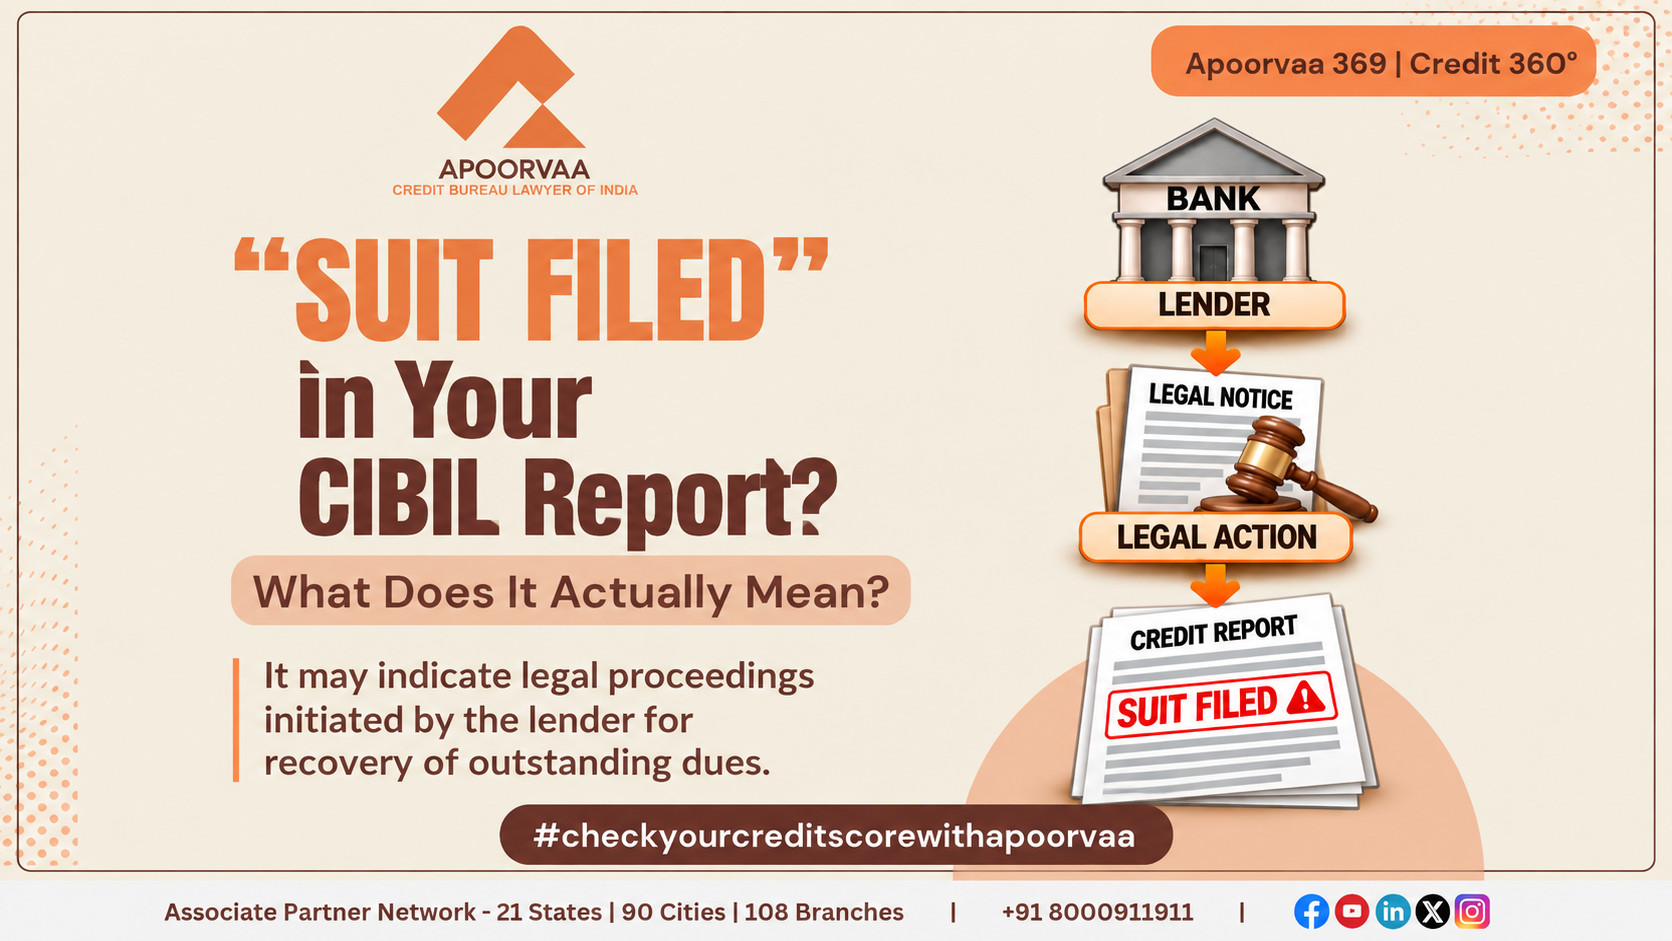
Suit Filed in CIBIL can become a serious concern when a customer has already repaid the loan but the latest Credit Report continues to reflect suit-related information.
The situation often looks like this:
Loan payment completed
Current Balance: ₹0
Suit Filed: Still appearing
Naturally, the customer asks:
“If nothing is outstanding now, why is Suit Filed still showing in my CIBIL Report?”
The answer requires more than checking whether the outstanding balance is zero.
A Credit Report contains different types of information about a credit facility. The current balance can represent the presently reported outstanding, while other account fields may reflect important events that occurred during the history of the facility.
Therefore, when Suit Filed continues to appear after repayment, the correct question is not simply:
“How can I remove Suit Filed?”
The more important question is:
“Is the information currently appearing in the Credit Report accurate and appropriately updated according to what actually happened with this account?”
That distinction is the starting point for professional Credit Report analysis.
What Does Suit Filed in CIBIL Actually Represent?
CIBIL’s consumer Credit Report guidance specifically contains a Suit-Filed / Wilful Default field.
According to CIBIL’s guidance, where a lender has filed a suit against the borrower, prescribed reporting applies. The possible values described include No Suit Filed, Suit Filed, Wilful Default and Suit Filed (Wilful Default).
This tells us that Suit Filed is not simply another term for:
an unpaid EMI, an overdue amount, a collection call or a recovery notice.
It relates to legal proceedings reported against the credit facility.
CIBIL also advises customers to review the account status appearing in their Credit Report and notes that Written-off, Settled and Suit Filed cases are not looked upon favourably by lenders.
Therefore, Suit Filed can be significant information when a lender evaluates a customer’s broader credit history.
Legal Notice Does Not Automatically Mean Suit Filed
This distinction is particularly important when analysing whether Suit Filed in CIBIL is appropriately reported.
During recovery, a lender may issue various communications to a customer.
There may be payment reminders, demand communications, collection correspondence or a legal notice.
But:
Receiving a legal notice does not automatically establish that a suit has been filed.
A legal notice and an actual legal proceeding are not identical events.
Therefore, merely establishing that a customer once received a legal notice is not sufficient, by itself, to conclude that a Suit Filed entry must necessarily be correct.
The actual legal and lender records behind the account need to be understood.
This distinction becomes particularly important in Credit Rectification cases where the customer disputes the very basis on which Suit Filed information is appearing.
Does Every Loan Default Become Suit Filed?
No.
A borrower can have delayed repayments or overdue amounts without a suit necessarily having been filed.
An overdue generally concerns an amount that was due but remained unpaid according to the credit facility’s repayment position.
A Suit Filed status concerns reported legal proceedings.
The two can be connected in the history of a problematic loan, but they do not mean the same thing.
Overdue ≠ Suit Filed
Similarly, a lender may take different recovery measures depending on the credit facility, amount involved, security, contractual rights, circumstances of default and applicable law.
Legal proceedings can form part of that recovery process, but every overdue account does not automatically progress to Suit Filed reporting.
Why Can Suit Filed Still Appear After Loan Repayment?
Consider a customer who had a loan account with unpaid dues.
During the period of default, legal proceedings were genuinely filed.
Later, the customer repaid the amount and the latest Credit Report now shows:
Current Balance: ₹0
But Suit Filed information continues to appear.
To understand this situation, two questions must be separated.
Question 1: What does the current balance show?
It relates to the amount currently being reported as outstanding under that account field.
Question 2: What does Suit Filed show?
It relates to legal proceedings reported in connection with the account.
These are different pieces of credit information.
Therefore:
Current Balance ₹0 does not automatically mean that every historical account event must disappear.
This is one of the most important concepts customers should understand before assuming that their Credit Report is incorrect.
Current Outstanding vs Historical Account Information
Suppose legal proceedings were initiated when a substantial amount remained unpaid.
The customer subsequently pays the dues.
The financial position of the account can change.
For example:
Earlier Current Balance: ₹4,50,000
Later Current Balance: ₹0
But the payment does not change the historical fact that a particular event may have occurred before repayment.
CIBIL’s own explanation of a Settled account helps demonstrate this broader credit-reporting distinction. CIBIL explains that after settlement, the amount overdue and current balance can become zero while the account continues to carry the Settled status.
Settlement and Suit Filed are different statuses, but the principle is useful:
Balance information and account-status information should not be interpreted as if they are the same field.
That is why a zero balance alone is not sufficient to determine whether the complete Credit Report has been appropriately updated.
Does Repayment Mean Suit Filed Must Be Deleted?
Not automatically.
This is where Credit Rectification needs to be approached carefully.
There is a major difference between:
correcting inaccurate information
and
trying to delete legitimate historical information.
If legal proceedings genuinely occurred and the Suit Filed information was accurately reported, subsequent repayment does not mean that the original event never happened.
Therefore, a professional Credit Rectification assessment should not begin with a promise that Suit Filed can simply be “removed.”
At the same time, this does not mean that every Suit Filed entry appearing after repayment must automatically be accepted as correct.
Subsequent developments matter.
For example, questions may arise around what happened to the legal proceeding after payment and whether the lender’s latest reporting appropriately reflects the current account and legal position.
That requires examination rather than assumption.
Historical Information Is Different From Outdated or Incorrect Information
This distinction is central to Suit Filed in CIBIL cases.
Correct historical information
Suppose a suit was genuinely filed and correctly reported.
The fact that the customer later repaid the loan does not automatically make the historical information false.
An adverse fact does not become an error merely because it affects the customer’s credit profile.
Potentially inaccurate or improperly updated information
A different situation arises where the reported information does not correspond with the actual account or legal records.
For example, the concern may relate to whether:
a suit was actually filed,
the reported information relates to the correct account,
the suit-related details are accurate,
or
material subsequent developments have been appropriately reflected.
These situations require a different analysis.
Negative information ≠ Automatically incorrect information.
But equally:
Historical information ≠ Permission for inaccurate information to remain uncorrected.
Professional assessment needs to identify which of these situations actually exists.
Why the Underlying Lender Records Matter
A common misunderstanding is that CIBIL independently decides what loan information should appear against a customer.
Credit Information Companies maintain credit information based substantially on information furnished by credit institutions.
RBI has previously emphasised that responsibility for reporting correct information and the accuracy of facts and figures rests with the concerned banks and financial institutions in the applicable suit-filed reporting context.
This is important when analysing a disputed Suit Filed entry.
If a customer believes the Credit Report is inaccurate, the issue cannot always be understood merely by looking at the visible CIBIL Report.
The relationship between:
the actual loan history,
the legal proceeding,
the lender’s records,
and
the information being reported to the Credit Information Company
may need to be understood.
That is why Credit Rectification is fundamentally an information-accuracy exercise, not simply a request to delete an unfavourable word.
Suit Filed, Settlement, Write-Off and Overdue Require Different Analysis
Customers frequently use these four expressions as though they represent the same problem.
They do not.
Overdue
An overdue generally concerns a payment that became due but remained unpaid.
Settlement
CIBIL explains Settled in the context of partial payment made with the lender’s consent against the total outstanding.
Write-Off
CIBIL’s consumer-report guidance separately identifies written-off amounts and Written-off/Settled status information.
Suit Filed
Suit Filed concerns reported legal proceedings relating to the credit facility.
Therefore:
Overdue ≠ Settlement ≠ Write-Off ≠ Suit Filed
An account can potentially contain more than one relevant event over its lifetime, which is why the complete account history must be analysed rather than treating all adverse information as one generic “CIBIL problem.”
Why Suit Filed Can Matter Even When the CIBIL Score Is Good
Consider this example:
CIBIL Score: 780
Current Balance: ₹0
Suit Filed information: Present on an older loan
If the customer checks only the Score, the profile may appear strong.
If the customer checks only the current balance, the loan may appear completely resolved.
But the Credit Report contains more information than these two numbers.
CIBIL states that Written-off, Settled and Suit Filed cases are not looked upon favourably by lenders.
This means account-level information can remain relevant to a lender’s credit-risk assessment even when the customer has a comparatively strong current Score.
However, this should not be converted into an exaggerated claim that every Suit Filed entry automatically results in loan rejection.
Suit Filed can be relevant adverse credit information, but lending decisions remain subject to the lender’s complete assessment and credit policy.
Why “Remove Suit Filed” Should Not Be the First Question
When customers approach Credit Rectification, the first request is often:
“Please remove Suit Filed from my CIBIL.”
But professional analysis should begin earlier than that.
Before discussing rectification, it is necessary to understand:
What actually happened on the account?
Was a suit genuinely filed?
What was reported at that time?
Was the loan subsequently paid, settled or otherwise resolved?
What happened to the legal proceeding?
What does the latest Credit Report currently show?
Does that reporting correspond with the underlying records?
Only after those questions are understood can the issue be properly classified as:
legitimate historical information
or
a potential Credit Report reporting discrepancy.
This diagnostic distinction is far more important than simply trying to change the visible status.
When Suit Filed Becomes a Genuine Credit Rectification Concern
A Suit Filed in CIBIL entry can require professional attention where there is a reasonable question about the accuracy or appropriate updating of the reported information.
For commercial reports, CIBIL’s own dispute-resolution material specifically identifies Suit Filed Status, Date of Suit and Suit Amount among account details that may be disputed where the information is inaccurate.
That does not mean every Suit Filed entry is disputable or removable.
It demonstrates that suit-related information contains specific reportable data which, like other credit information, needs to be accurate.
Therefore, the objective of professional Credit Rectification should be:
Understand the information → establish the actual account position → identify a genuine reporting discrepancy, if one exists → address the accuracy of the Credit Report.
It should never begin with a guarantee that legitimate historical information can be deleted.
What If the Legal Case Was Closed, Withdrawn or Disposed After Payment?
This is one of the most important questions when Suit Filed in CIBIL continues to appear after repayment.
Suppose the lender genuinely initiated legal proceedings when the loan was unpaid. Later, the customer cleared the dues and the legal proceeding was subsequently withdrawn, closed, disposed of or otherwise concluded.
The customer may reasonably ask:
“If the loan is paid and the legal case is also no longer pending, what should my Credit Report show now?”
This cannot be answered simply by looking at the current balance.
The account needs to be understood across three different stages:
What was the position when the suit was filed?
What happened to the loan after the suit was filed?
What is the latest position being reported by the lender?
The historical fact that proceedings were once filed and the present status of those proceedings are related, but they are not necessarily identical pieces of information.
Therefore, professional analysis should examine whether the latest Credit Report appropriately represents the relevant developments rather than assuming either automatic deletion or permanent unchanged reporting.
Does Closed Loan Mean the Credit History Is Completely Clear?
Not necessarily.
The word “Closed” can itself create confusion.
A customer may see that a loan has been paid or closed and assume:
“The account is closed, so no previous adverse information should matter anymore.”
But closing a loan and rewriting its historical credit information are different concepts.
If the account genuinely experienced substantial overdue, settlement, write-off, legal proceedings or another reportable event, closing the financial obligation does not automatically establish that those events never occurred.
This is why:
Closed Account ≠ Automatically Clean Historical Record
At the same time, if the account has been closed and the Credit Report is still reflecting information that is factually inconsistent with the lender’s current records, that can require further examination.
The key issue remains accuracy and appropriate updating.
What Should Be Verified When Suit Filed Continues After Repayment?
When a customer approaches Apoorvaa with Suit Filed in CIBIL after repayment, looking only at a screenshot of the status may not explain the complete issue.
The account has to be understood in context.
Relevant questions include whether the legal proceeding was actually filed, which credit facility it concerned, what the reported suit-related information represents, how the dues were ultimately resolved, what happened to the legal proceeding subsequently, and what the lender’s current records show.
This does not mean that every customer needs the same rectification action.
In some cases, the reported information may represent legitimate historical credit information.
In another case, there may be a material inconsistency requiring closer review.
The correct diagnosis must come before rectification.
Suit Filed vs Wilful Default: A Critical Difference
Another area where customers can misunderstand their Credit Report is the relationship between Suit Filed and Wilful Default.
They should not be treated as interchangeable.
CIBIL’s consumer Credit Report guidance itself provides separate values within the Suit-Filed/Wilful Default field, including:
No Suit Filed
Suit Filed
Wilful Default
Suit Filed (Wilful Default)
This distinction matters because a Suit Filed account should not automatically be labelled a Wilful Default account.
Suit Filed ≠ Wilful Default
Wilful Default has a specific regulatory meaning and framework. It should not be inferred simply because a customer experienced repayment problems or because legal proceedings were initiated.
This distinction is particularly important when analysing potentially serious information appearing in a Credit Report.
Can Suit Filed Affect Loan Eligibility After Repayment?
It can remain relevant to credit assessment, but there should be no blanket statement that Suit Filed automatically means loan rejection.
A lender assessing a fresh application may evaluate the customer’s complete credit profile rather than considering only the current CIBIL Score.
That assessment can include the underlying account history, existing obligations, repayment capacity, income or financial position, proposed loan amount, security or collateral where applicable and the lender’s internal credit policy.
Therefore, two assumptions should be avoided.
Assumption 1:
“Suit Filed is showing, so no lender can ever approve my loan.”
That is too broad.
Assumption 2:
“My loan is paid and my CIBIL Score is good, so Suit Filed cannot affect a new application.”
That is also too broad.
The more accurate position is that Suit Filed can represent significant credit information that a lender may consider as part of its overall underwriting assessment.
Why Repeated Loan Applications May Not Solve the Real Problem
When a customer has repaid an old loan and receives difficulty with a fresh credit application, the immediate reaction is sometimes to apply with another lender.
But if the underlying Credit Report contains significant account information that has not been understood, repeatedly changing lenders may not address the real issue.
The customer should first understand:
Is the report accurately showing legitimate historical information?
or
Is there a genuine reporting inconsistency requiring attention?
That distinction can be more valuable than focusing only on the latest Score or repeatedly applying for new credit.
Correct Historical Information vs Genuine Reporting Error
This distinction is at the heart of responsible Credit Rectification.
Consider two customers.
Customer A
Legal proceedings were genuinely filed during default. The reported information corresponds with the underlying account and legal history, and subsequent developments have been appropriately reflected.
The customer may dislike the adverse history, but that alone does not make the information incorrect.
Customer B
The Credit Report contains Suit Filed information that appears inconsistent with the actual account, legal proceeding or lender records, or relevant subsequent information has not been appropriately reflected.
This may represent a genuine reporting concern requiring further examination.
The two customers should not be treated identically.
Credit Rectification should correct genuine reporting problems—not create a false credit history.
Why “Guaranteed Suit Filed Removal” Should Be Treated Carefully
Customers searching online for solutions may encounter claims such as:
“Remove Suit Filed from CIBIL.”
“Delete negative CIBIL status.”
“Guaranteed CIBIL correction.”
These statements can create unrealistic expectations.
Whether information can appropriately be corrected depends on what actually happened and whether the information currently being reported is inaccurate or has not been properly updated.
If the information accurately reflects legitimate credit history, it should not be represented as an error merely because it is adverse.
A professional Credit Rectification service should therefore not begin with a guarantee of deletion.
It should begin with:
Credit Report analysis and identification of the actual reporting issue.
Why the Root Cause Matters More Than the Visible Status
Suppose two customers both have Suit Filed in CIBIL.
At first glance, their reports appear to have the same problem.
But the underlying circumstances could be completely different.
One may have had genuine legal proceedings followed by repayment.
Another may dispute whether the reported suit information corresponds with the actual facility.
A third may have a dispute about subsequent updating.
A fourth may have multiple adverse account events involving overdue, settlement, write-off and legal proceedings.
The visible words “Suit Filed” alone do not tell us which situation exists.
That is why Apoorvaa’s approach to Credit Rectification focuses first on understanding the root cause behind the reported information.
Frequently Asked Questions About Suit Filed in CIBIL
- What does Suit Filed in CIBIL mean?
It relates to legal proceedings reported in connection with a credit facility. It should not be treated as another word for overdue or merely receiving a legal notice.
- My loan balance is zero. Why is Suit Filed still showing?
A zero current balance and historical/legal account information represent different aspects of the credit facility. Repayment does not automatically erase every correctly reported historical event.
- Is a legal notice enough to report Suit Filed?
A legal notice should not automatically be equated with a suit having been filed. The actual proceeding and the basis of the reported information need to be understood.
- Can Suit Filed be removed after full payment?
Full payment alone does not establish that correctly reported historical information must be deleted. Where the information is inaccurate or has not been appropriately updated, however, the reporting position may require review.
- What if the case was withdrawn or closed after payment?
The subsequent legal and account position becomes relevant. The latest Credit Report should be assessed against the underlying lender and legal records to understand whether the information is being appropriately reported.
- Is Suit Filed the same as Write-Off?
No. Write-Off and Suit Filed represent different credit/account events and should not be used interchangeably.
- Is Suit Filed the same as Settlement?
No. A settlement concerns how dues were resolved with the lender, while Suit Filed concerns reported legal proceedings. An account may have a more complex history involving multiple events, but the terms themselves are different.
- Is Suit Filed the same as Wilful Default?
No. Wilful Default has a specific regulatory meaning and should not automatically be inferred from Suit Filed.
- Will Suit Filed automatically cause loan rejection?
Not necessarily. It can be relevant adverse credit information, but loan approval depends on the lender’s complete underwriting assessment and credit policy.
- Can I have a good CIBIL Score while Suit Filed appears in an account?
The CIBIL Score and account-level information are different components of the overall credit profile. This is why the complete Credit Report should be understood rather than relying only on the Score.
Apoorvaa’s Approach: Understand the Report Before Rectification
At Apoorvaa – Credit Bureau Lawyer of India, we believe that a Credit Rectification case should begin with one fundamental question:
What is actually wrong in the Credit Report?
Not every negative entry is an error.
Not every old entry should automatically be deleted.
And not every zero-balance account necessarily means that all historical information should disappear.
When Suit Filed in CIBIL continues after repayment, the objective should be to understand the complete account history and determine whether the information represents:
genuine and appropriately reported credit history,
or
a genuine accuracy or updating concern requiring professional attention.
This distinction helps ensure that Credit Rectification remains focused on the accuracy of credit information rather than creating unrealistic expectations about deleting legitimate history.
Final Takeaway
A customer may repay the entire loan and see:
Current Balance: ₹0
while still finding:
Suit Filed
in the Credit Report.
Those two pieces of information do not necessarily contradict each other.
One concerns the presently reported financial position of the account. The other may relate to legal proceedings that occurred during its history.
The key question is therefore not:
“Why hasn’t CIBIL automatically deleted Suit Filed?”
It is:
“Does my latest Credit Report accurately and appropriately reflect what actually happened before and after repayment?”
If the information is genuine and correctly reported, an adverse historical event should not automatically be called an error.
If the information is inaccurate, inconsistent or has not been appropriately updated, professional Credit Report assessment can help identify whether a genuine Credit Rectification issue exists.
Professional Credit Report Assessment
If your loan has already been repaid but Suit Filed in CIBIL is still appearing, Apoorvaa can help assess the complete Credit Report and understand whether the information represents legitimate historical reporting or a genuine reporting concern requiring professional attention.
📞 +91 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of correctly reported credit history, a particular CIBIL Score, loan eligibility or loan approval. Lending decisions remain subject to the lender’s applicable policies and assessment.
Related Credit Education