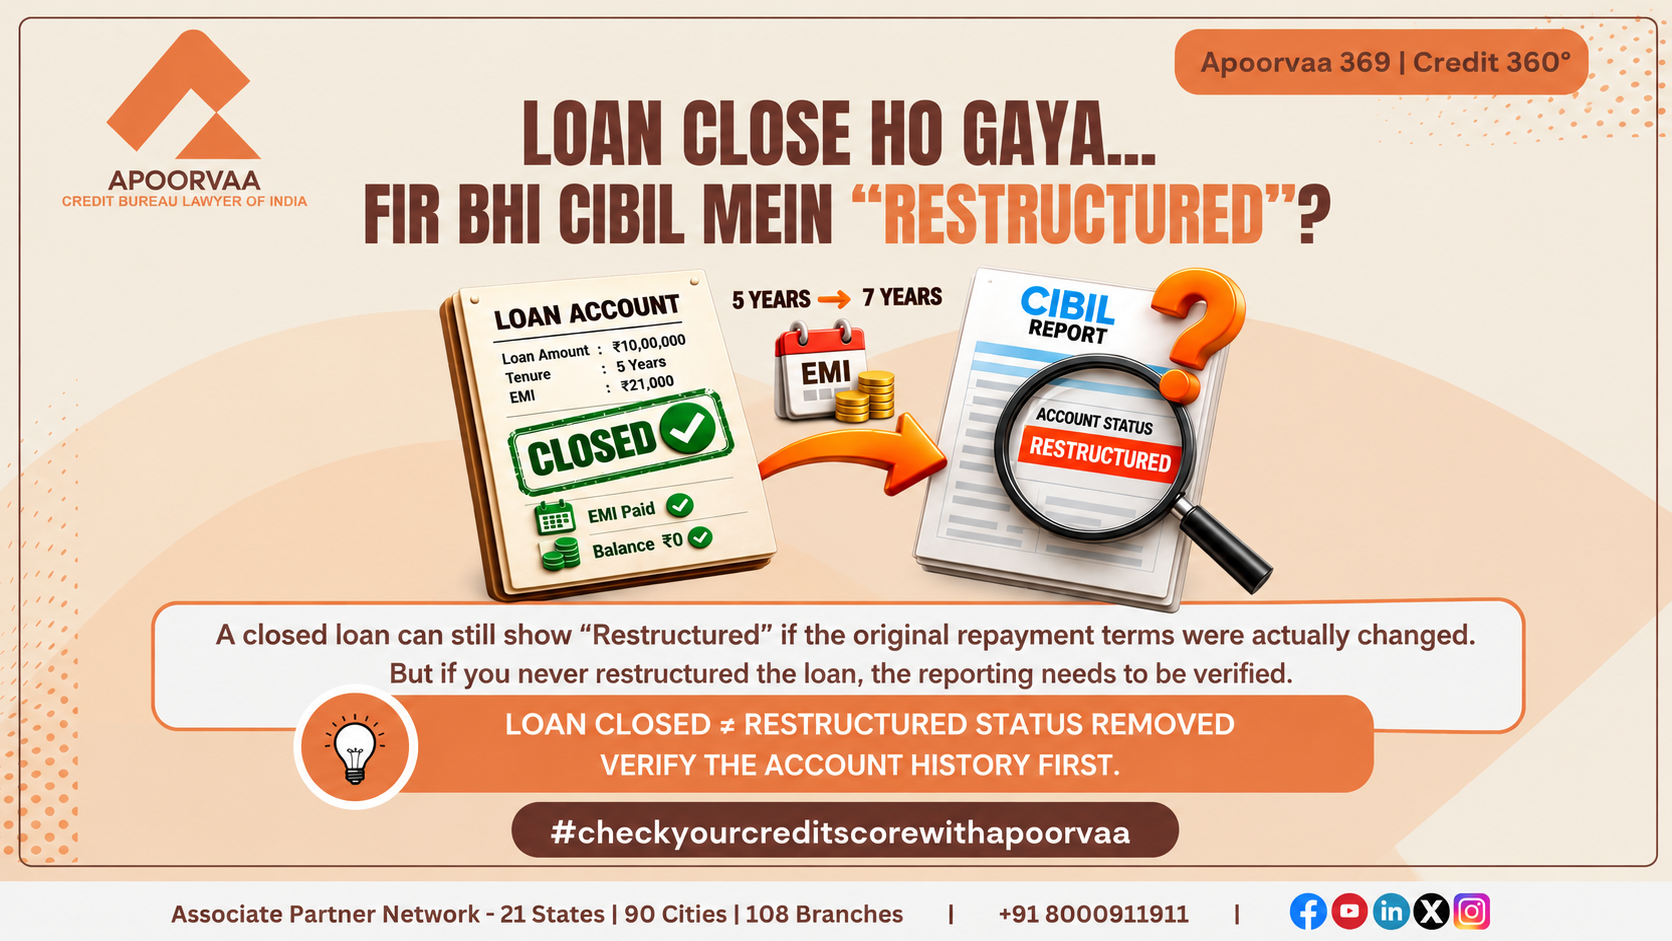
“My loan is fully repaid and closed. Why does my CIBIL Report still show Restructured?”
This situation requires more than checking whether the outstanding balance has become zero.
A borrower may have completed repayment, received a closure letter or NOC and no longer owe any amount under the loan.
Yet the Credit Report may contain a restructuring-related classification against the same account.
At first glance, these two pieces of information may appear contradictory.
They are not necessarily contradictory.
Loan closure describes what eventually happened to the facility. Restructuring describes an event that may have occurred during the life of that facility.
Therefore, when Restructured in CIBIL Report appears against a subsequently closed loan, the first objective should not be to seek its removal.
The first objective should be to establish whether restructuring actually occurred and whether the reported information accurately represents the underlying account history.
That requires examination of the Credit Report together with the lender’s account documentation.
- What Exactly Does Loan Restructuring Mean?
Loan restructuring should not be interpreted simply as “the EMI changed” or “the tenure increased.”
Under the applicable regulatory framework, restructuring broadly involves a lender granting concessions for economic or legal reasons relating to the borrower’s financial difficulty.
Depending on the facility and circumstances, restructuring may involve modification of original credit terms concerning matters such as:
- Repayment period
- Repayment schedule
- Instalment amount
- Amount payable
- Interest terms
- Rollover of certain facilities
- Other contractual terms forming part of the restructuring arrangement
The reason behind the modification is important.
A change in a loan term does not automatically prove restructuring.
For example, an interest rate on a floating-rate facility may change according to the original contractual mechanism or applicable regulatory framework.
That is fundamentally different from concluding that the lender granted a concession because the borrower was experiencing financial difficulty.
Similarly, an extension of tenure should not be examined in isolation. The contractual basis, lender communication and circumstances surrounding that extension matter.
Therefore:
Changed EMI ≠ Automatically Restructured
Changed Interest Rate ≠ Automatically Restructured
Extended Tenure ≠ Automatically Restructured
The underlying transaction and documentation determine what actually occurred.
- Does an EMI Need to Bounce Before Restructuring Can Occur?
No.
This is an important distinction when analysing a disputed restructuring classification.
A borrower may say:
“None of my EMIs bounced, so my account could never have been restructured.”
That conclusion is not necessarily correct.
Financial difficulty can exist even before an actual payment default occurs.
A borrower and lender may address emerging repayment difficulty by formally modifying the facility under an applicable restructuring arrangement.
Therefore, the absence of an EMI bounce does not automatically prove that restructuring never occurred.
The opposite is equally important.
An EMI bounce does not itself prove restructuring.
A missed or delayed instalment is a repayment event.
Restructuring involves modification of the credit arrangement under the relevant circumstances.
The two should not be treated as interchangeable.
- Can a Closed Loan Still Show Restructured?
Yes, where restructuring genuinely occurred during the loan’s lifecycle and the applicable reporting accurately reflects that history.
Consider this simplified sequence:
Original Loan → Financial Difficulty → Restructuring → Revised Repayment → Full Repayment → Loan Closure
At the end of this sequence, the loan may be completely repaid.
The Current Balance may be zero.
The account may have a closure date.
The borrower may also possess an NOC or closure confirmation.
But none of these later events automatically establishes that the earlier restructuring never occurred.
This is why a closed loan and historical restructuring information can coexist.
The correct analysis requires separating:
Current Account Position
What is the position of the facility now?
Has repayment been completed?
Is any Current Balance or Amount Overdue still being reported?
Has the account been reported as closed?
Historical Account Information
What happened while the loan was active?
Were the original repayment terms modified through restructuring?
Was a revised repayment arrangement documented?
How did the borrower subsequently service the facility?
Both categories of information can be relevant to the same credit account.
- Restructured vs Closed: Why Both Can Be Relevant
The easiest way to understand this distinction is to compare two hypothetical accounts.
Account A — Genuine Restructuring Followed by Closure
A borrower obtains a loan under defined sanction terms.
Later, the borrower experiences financial difficulty.
The lender and borrower enter into a restructuring arrangement under which the applicable repayment terms are modified.
The borrower then services the loan according to the revised arrangement and eventually repays it completely.
The account is closed.
In this case:
Closure is true.
And:
Historical restructuring is also true.
Successful repayment after restructuring does not make the earlier restructuring event inaccurate.
Account B — Loan Closed Without Restructuring
Another borrower obtains a loan and continues servicing the facility under the applicable contractual arrangement.
Certain ordinary changes may occur during the loan period, but the borrower does not enter into a restructuring arrangement because of financial difficulty.
The loan is ultimately repaid and closed.
If a restructuring-related classification nevertheless appears against this account, the reporting may require closer examination.
The two accounts may have the same final outcome—full repayment and closure—but materially different histories.
This is why “My loan is closed” is not enough information to determine whether “Restructured” is correct or incorrect.
- What If I Never Restructured the Loan?
This is where document-level analysis becomes particularly important.
Suppose a borrower sees Restructured in the Credit Report but states:
“I never requested restructuring.”
That statement is relevant, but a professional assessment should go further.
The account records should establish whether the reported classification corresponds with what actually occurred.
Original Sanction Letter
The sanction letter helps establish the original terms of the credit facility.
Depending on the product, it may identify matters such as the sanctioned amount, repayment period, applicable interest structure and other important contractual terms.
This provides the starting point for comparison.
Restructuring Letter or Agreement
If formal restructuring occurred, there may be documentation concerning the revised arrangement.
The nature and availability of such documentation can be important when determining what was agreed between the borrower and lender.
Revised Repayment Schedule
Where restructuring modified the repayment arrangement, a revised schedule may help establish how the facility was expected to be serviced after modification.
However, the mere existence of a different schedule should not be interpreted without understanding why it changed.
Loan Account Statement and Repayment History
The account statement can help establish how the facility was actually serviced over time.
It may also assist in comparing the original repayment arrangement with subsequent account activity.
But repayment behaviour alone does not conclusively establish whether restructuring occurred.
Closure Letter or NOC
A closure document is important evidence of the eventual position of the facility.
However:
A closure letter proves closure; it does not necessarily prove that restructuring never occurred earlier.
This distinction is critical.
Complete Credit Report
Finally, the complete Credit Report should be examined rather than focusing on a single word or field.
The restructuring-related information should be read alongside:
- Account status
- Current Balance
- Amount Overdue
- Date-related information
- Repayment history
- Written-off/settled information, where applicable
- Other account-level information reported by the lender
The objective is to determine whether the documents and the Credit Report tell a consistent story.
- Why an Interest-Rate or EMI Change Should Not Automatically Be Called Restructuring
This distinction is particularly important in professional Credit Report analysis.
Suppose a borrower’s EMI increases because the applicable floating interest rate changes.
Or the loan tenure changes under the contractual mechanism applicable to that facility.
Those facts alone do not establish that the borrower received a restructuring concession because of financial difficulty.
Conversely, a borrower may have entered into a formal restructuring arrangement involving modification of repayment obligations even though the account had not yet experienced an EMI bounce.
Therefore, professional analysis should avoid shortcuts such as:
“The tenure changed, therefore it was restructured.”
or:
“No EMI bounced, therefore it could not have been restructured.”
Neither conclusion is reliable without understanding the contractual and documentary context.
The correct question is:
What caused the original loan terms to change, under what arrangement were they changed, and how did the lender classify that event?
That question helps distinguish an ordinary contractual development from a genuine restructuring event—and a genuine restructuring event from potentially inaccurate credit reporting.
- Can an Incorrect Restructured Status Be Corrected?
Yes, where the restructuring-related information is established to be inaccurate.
But the starting point should not be:
“How can Restructured be removed from my CIBIL Report?”
The correct starting point is:
“Was the loan actually restructured, and does the reported information accurately represent the account history?”
This distinction is fundamental to Credit Rectification.
If the borrower genuinely underwent restructuring and the lender has accurately reported the event, successful repayment and subsequent closure do not automatically make that historical information incorrect.
An adverse classification is not necessarily an inaccurate classification.
However, if the borrower never underwent restructuring and the lender’s verified records do not support the reported information, the discrepancy may require correction.
Potential situations requiring examination can include:
- No restructuring arrangement exists in the lender’s records.
- The reported classification appears inconsistent with the underlying loan documents.
- An ordinary contractual modification appears to have been treated as restructuring.
- The lender and Credit Report contain materially inconsistent account information.
- The borrower disputes the restructuring classification and supporting records indicate a different account history.
The objective is not automatic removal.
The objective is accurate credit reporting.
- Why Lender Verification Matters
Banks, NBFCs and other Credit Institutions furnish account information to Credit Information Companies.
Therefore, when a borrower disputes restructuring-related information appearing in a CIBIL Report, the lender’s underlying records become particularly important.
TransUnion CIBIL provides a mechanism through which consumers can dispute potentially inaccurate information in their reports.
However, a Credit Information Company does not simply rewrite lender-furnished account information because the borrower disagrees with it.
The disputed information generally needs to be verified through the concerned Credit Institution.
This means that a borrower stating:
“My loan is closed, therefore Restructured should be removed”
does not by itself establish an error.
Likewise, the presence of Restructured in the Credit Report should not automatically end the analysis if credible account documents indicate that no restructuring occurred.
The lender records and the credit information should correspond.
- Document Consistency: What Should the Account History Show?
Professional Credit Report assessment becomes especially important where different documents appear to tell different stories.
Consider this example:
The original sanction letter shows a five-year repayment period.
A later repayment schedule shows a seven-year period.
The Credit Report contains a restructuring-related classification.
Does that prove restructuring?
Not by itself.
The next question is:
Why did the repayment period change?
Was there a restructuring arrangement arising from financial difficulty?
Was the change made under another contractual or regulatory mechanism?
Was a revised agreement issued?
What did the borrower accept?
How did the lender record the event internally?
The answer cannot reliably be established by looking at the changed tenure alone.
A Professional Comparison May Examine
Original Sanction Terms
What was originally agreed?
Subsequent Loan Documentation
Were the original contractual obligations formally modified?
Reason for Modification
Was the change associated with financial difficulty and a concession, or did it arise for another reason?
Repayment History
How was the account serviced before and after the change?
Closure Documentation
What was the eventual position of the facility?
Credit Report Information
How has the lender represented the account to the Credit Information Company?
The purpose of comparing these records is not to search for a technical reason to remove legitimate information.
It is to establish whether the Credit Report accurately reflects the underlying account.
- Verification First, Rectification Second
This principle is particularly important for restructuring-related cases.
Suppose a borrower approaches a Credit Rectification professional because a closed account shows Restructured.
There are two possible broad outcomes.
Outcome 1: Restructuring Is Supported by the Records
The documents establish that the original credit arrangement was genuinely restructured.
The borrower subsequently complied with the revised arrangement and ultimately repaid the loan.
In this situation, the loan’s successful closure does not automatically make the historical restructuring classification inaccurate.
Professional rectification should not be represented as a mechanism for erasing legitimate credit history.
Outcome 2: Restructuring Is Not Supported by the Records
The borrower disputes restructuring, and the available lender records indicate that the facility did not undergo the restructuring represented in the Credit Report.
In such circumstances, the reporting discrepancy may require investigation and correction through the applicable framework.
That is why the correct sequence is:
Credit Report → Account Documents → Verification → Identify Discrepancy → Rectification, Where Justified
Not:
Negative Status → Automatic Removal Request
This distinction protects both the accuracy of the Credit Report and the credibility of professional Credit Rectification.
- Does a Restructured Loan Affect Future Loan Eligibility?
A restructuring history may be relevant when a borrower applies for new credit.
However, it should not be presented as an automatic loan-rejection trigger.
A prospective lender may consider previous restructuring as one factor when assessing the borrower’s earlier financial stress and credit behaviour.
The final underwriting decision can also depend on several other factors, including:
- Current income or business cash flow
- Existing financial obligations
- Overall repayment history
- Recent credit behaviour
- Loan amount requested
- Type and purpose of credit
- Security or collateral
- Banking conduct
- Borrower’s overall credit profile
- Lender’s internal credit and risk policies
Different lenders may also assess the same historical information differently.
Therefore:
Restructured ≠ Automatic Loan Rejection
But:
Loan Closed ≠ Restructuring History Becomes Irrelevant
The complete credit profile matters.
- Why the Complete Credit Report Matters Before a New Loan Application
Borrowers frequently focus almost entirely on their credit score.
But a score is not the complete credit profile.
The account-level information in the Credit Report may provide additional context regarding how previous facilities were serviced and resolved.
For example, a borrower may have:
- A satisfactory current credit score
- No present overdue amount
- A closed loan
- A historical restructuring classification
A future lender may evaluate these pieces of information together rather than relying on one number.
This is why borrowers should understand their Credit Report before making a significant new credit application.
The purpose is not to attempt deletion of every unfavourable historical event.
It is to identify whether the information being presented to prospective lenders is complete and accurate.
- When Does Professional Credit Rectification Become Relevant?
Professional Credit Rectification becomes relevant when there is a reasonable basis to question the accuracy of the reported information.
For example, professional examination may be appropriate when:
- The borrower does not recognise the restructuring classification.
- The sanction and subsequent loan documents do not appear to support restructuring.
- The reported information conflicts with lender-issued records.
- There is uncertainty about whether a modification was an actual restructuring or another contractual change.
- Multiple account fields appear inconsistent with one another.
The professional role is first to understand the discrepancy.
Only then should the question of rectification arise.
At Apoorvaa – Credit Bureau Lawyer of India, this distinction is central:
We must first establish what the lender was supposed to report based on the verified account history.
If the lender’s reporting accurately represents the account, there may be no legitimate basis to seek its removal merely because it could influence future underwriting.
If the reporting is inaccurate, the correction process should focus on bringing the Credit Report into alignment with the verified account information.
Frequently Asked Questions
- My loan is fully paid and closed. Why does the CIBIL Report still show Restructured?
Because closure and restructuring may describe different stages of the same loan. The loan can eventually be repaid and closed while retaining accurate information that restructuring occurred earlier.
- Does a zero outstanding balance mean Restructured should disappear?
No. A zero balance establishes the reported current financial position. It does not automatically erase accurate historical information about how the facility was managed.
- Does an EMI have to bounce before a loan can be restructured?
No. Financial difficulty can exist before an actual payment default occurs. Conversely, an EMI bounce alone does not establish that restructuring took place.
- My loan tenure increased. Does that prove restructuring?
Not automatically. The reason for the tenure change, contractual framework, lender documentation and surrounding circumstances need to be understood.
- My interest rate changed. Does that mean the loan was restructured?
Not necessarily. Certain interest-rate changes can arise under the original contractual structure or applicable framework. A rate change alone should not automatically be treated as proof of restructuring.
- What if I never requested or agreed to restructuring?
The underlying documentation should be examined. The sanction letter, subsequent agreements or communications, repayment history, loan statements, closure records and Credit Report may help establish whether restructuring actually occurred.
- Can an incorrect Restructured classification be corrected?
Yes, where the information is established to be inaccurate through the applicable lender/CIC verification and correction framework.
- Can an accurate restructuring history be removed because the loan is now closed?
Loan closure by itself does not make an accurate historical restructuring event incorrect. Credit Rectification should not be represented as a way to erase legitimate credit history.
- Will Restructured automatically cause my next loan to be rejected?
No. A prospective lender may consider restructuring history, but the final credit decision can involve multiple factors including income or cash flow, repayment behaviour, existing debt, loan amount, product type, collateral and internal lending policies.
My Perspective
When a borrower tells me:
“Sir, I have completely repaid this loan. Why is Restructured still appearing?”
I believe the first response should not be a promise to remove it.
We first need to understand the history of the account.
Was the original loan arrangement genuinely restructured?
Why were the terms changed?
What does the sanction letter say?
Was there a restructuring letter or revised arrangement?
What does the repayment history show?
What does the lender’s closure documentation establish?
And finally, does the Credit Report accurately represent those events?
If restructuring genuinely occurred, subsequent successful repayment is important—but it does not make that historical event untrue.
If restructuring never occurred and the lender’s records support the borrower’s position, the reporting deserves proper investigation.
That is why Credit Rectification should always begin with verification, not assumption.
Final Takeaway
If your loan is fully repaid and closed but your CIBIL Report still shows a restructuring-related classification, do not judge the account from one word alone.
Understand the complete sequence.
Original Loan → Modification, if any → Repayment History → Final Repayment → Closure
Then determine whether the modification was genuinely a restructuring event.
Remember:
Loan Closed ≠ Restructuring Never Happened
Changed EMI/Tenure ≠ Automatically Restructured
EMI Bounce ≠ Proof of Restructuring
No EMI Bounce ≠ Proof That Restructuring Never Occurred
Full Repayment ≠ Automatic Removal of Accurate Historical Information
And equally:
Restructured Showing ≠ Automatically Accurate
The correct objective is to ensure that the Credit Report and the verified account records tell the same story.
Professional Credit Report Assessment & Credit Rectification
Is your loan already closed but your CIBIL Report still showing a restructuring-related classification?
If you are uncertain whether the information matches your sanction terms, loan documents, repayment history and closure records, professional examination may help establish whether a genuine reporting discrepancy exists.
Apoorvaa provides professional Credit Report assessment and Credit Rectification services for individuals and businesses where material credit information requires verification and, where justified, correction.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of accurately reported information, an increase in any credit score or approval of a future loan application.
Related Credit Education