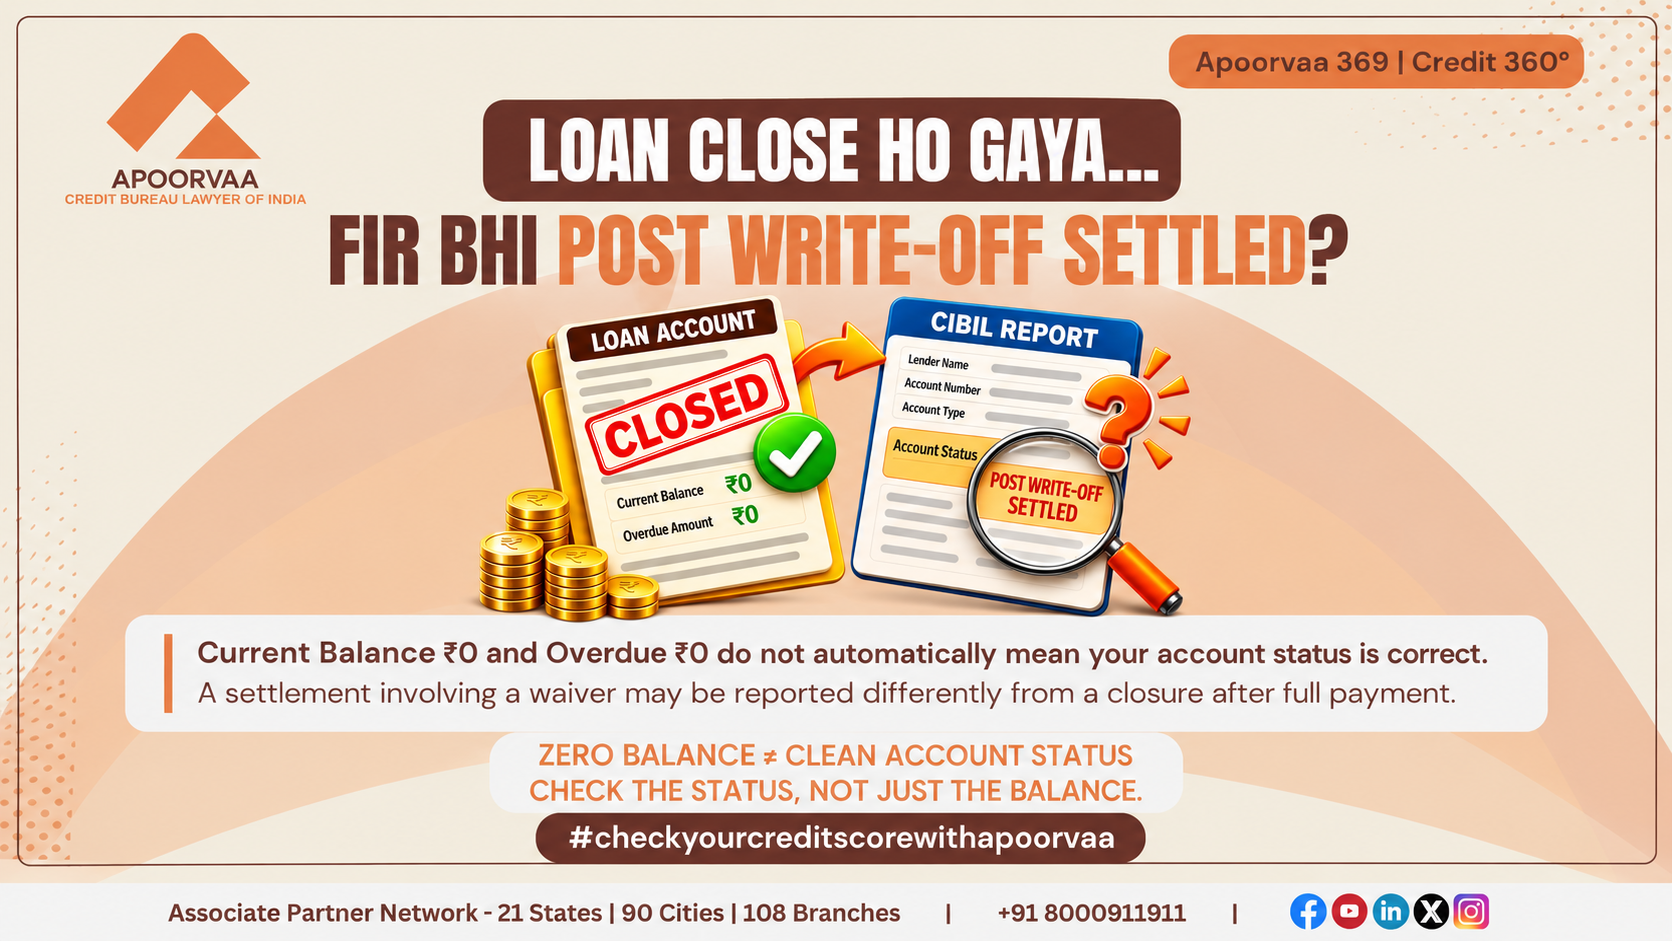
“My loan is closed and the outstanding balance is zero. Why does CIBIL still show Post Write-Off Settled?”
A borrower completes payment to the lender and subsequently checks their CIBIL Report.
The account reflects:
Current Balance: ₹0
Amount Overdue: ₹0
Written-off/Settled Status: Post Write-Off Settled
The borrower may reasonably believe that once the outstanding amount becomes zero, the account should automatically reflect a normal Closed status.
However, this assumption overlooks an important aspect of credit-information reporting.
A Credit Report contains both current financial information and historical account classifications.
The Current Balance and Amount Overdue describe the account’s reported financial position. A written-off or settlement-related classification may describe significant events in the account’s earlier repayment history.
Consequently, Post Write-Off Settled in CIBIL Report may remain visible even after the borrower completes the required payment.
The key question is whether the reported classification accurately corresponds with the lender’s verified account history.
This distinction is central to professional Credit Report interpretation and Credit Rectification.
- What Does Post Write-Off Settled Mean in a CIBIL Report?
Post Write-Off Settled is a reporting classification associated with a credit facility that was written off and subsequently settled.
TransUnion CIBIL’s published Credit Report terminology includes Post (WO) Settled among the possible written-off and settled status classifications.
Understanding the classification requires distinguishing three events.
The Write-Off
A lender may record a write-off after an account experiences repayment difficulties and the relevant accounting conditions are met.
A technical write-off is an accounting treatment. It does not, by itself, extinguish the underlying debt or waive the lender’s claims.
The Reserve Bank of India’s framework on compromise settlements and technical write-offs expressly distinguishes technical write-offs from a waiver of the lender’s claims.
The Settlement
A settlement may involve an agreement under which the lender accepts an agreed payment to resolve the account.
Where the lender agrees to sacrifice part of its claim, the arrangement may constitute a compromise settlement.
The borrower may complete the agreed payment and have no further amount due under that arrangement.
However, completing a settlement does not necessarily mean the original loan was repaid in full without a compromise.
The Post Write-Off Settlement
Where an account was written off and subsequently resolved through a settlement, the lender may report the corresponding historical classification.
The result can be a Credit Report containing a zero Current Balance alongside Post Write-Off Settled.
The zero balance and the historical classification are not necessarily contradictory.
They may describe different aspects of the same account.
- Why Does Post Write-Off Settled Show Even When the Balance Is Zero?
A common interpretation error occurs when a borrower treats the Current Balance as the only meaningful field in the Credit Report.
Consider the following illustrative account position:
| Credit Report field | Reported information |
| Current Balance | ₹0 |
| Amount Overdue | ₹0 |
| Written-off/Settled Status | Post Write-Off Settled |
| Repayment history | Reflects the periods reported by the lender |
| Account closure information | Subject to the lender’s reported records |
This example is illustrative and does not describe a specific customer’s account.
The Current Balance of ₹0 indicates that no current balance is being reported.
The Amount Overdue of ₹0 indicates that no overdue amount is being reported in that field.
Neither figure independently establishes whether the account was previously written off or settled.
How the Account May Reach This Position
An account may experience repayment difficulties.
The lender may subsequently record a write-off.
The borrower and lender may later enter into a compromise settlement.
Once the agreed settlement payment is completed, the lender may update the financial fields to reflect no present outstanding balance.
At the same time, the lender may retain the applicable settlement-related classification.
The account therefore contains two different categories of information:
Present financial position: What amount is currently reported?
Historical repayment classification: How was the account resolved?
Both are relevant to the interpretation of the Credit Report.
A zero balance should not be treated as automatic evidence that every historical classification must disappear.
- Post Write-Off Settled vs Settled vs Closed: What Is the Difference?
These classifications can indicate different account histories.
| Classification | General meaning | Key interpretation |
| Closed | Account reported as closed | Does not, by itself, describe every historical repayment event |
| Settled | Account resolved through a settlement arrangement | Settlement terms and lender records matter |
| Post Write-Off Settled | Settlement associated with an earlier write-off | Both the write-off and subsequent settlement are relevant |
A borrower may use the word closed in everyday conversation to mean that the lender is no longer requesting payment.
However, that does not necessarily establish the precise classification that should appear in the Credit Report.
A loan can be financially resolved through a settlement while its historical reporting continues to identify the nature of that resolution.
Why This Distinction Matters
Suppose a borrower pays the amount agreed in a final settlement letter.
The borrower may reasonably say:
“I have paid everything the bank asked me to pay.”
That statement may be accurate.
But it does not necessarily establish that the borrower repaid the entire amount otherwise due without a compromise.
The settlement letter, lender’s ledger and relevant account records may show that part of the claim was waived.
Where a genuine compromise settlement followed a write-off, the historical classification may accurately reflect that sequence.
Conversely, if the reported classification does not match the verified account history, the discrepancy may require examination.
A payment confirmation establishes payment. It does not necessarily establish the correct credit-reporting classification.
- Does Every Waiver Mean the Account Was Settled?
No.
This distinction is particularly important when examining whether Post Write-Off Settled has been reported correctly.
Not every reduction, reversal or adjustment in an account is necessarily a compromise settlement.
For example, a lender may reverse a charge that was incorrectly applied or make another routine adjustment under the applicable account terms.
Such an adjustment should not automatically be equated with a negotiated compromise of the underlying debt.
On the other hand, a lender may agree to accept less than the amount otherwise due as part of a compromise settlement.
These situations may have different reporting implications.
Why the Nature of the Payment Matters
Consider two hypothetical borrowers.
Borrower A: The lender writes off the account and later agrees to accept a reduced amount through a compromise settlement.
Borrower B: The lender makes an ordinary correction to an incorrectly charged fee, and the borrower pays the remaining amount due.
Both borrowers may ultimately have a zero outstanding balance.
But the financial and contractual events leading to that position are not necessarily the same.
The correct reporting classification depends on the actual account history and the applicable reporting requirements.
It cannot be established merely by identifying that some amount was reduced or waived.
- What If I Paid the Full Amount but the Report Still Shows Post Write-Off Settled?
This is one of the most important situations requiring account-level examination.
A borrower may state:
“I paid the complete amount, including interest and charges. Why is my report still showing Post Write-Off Settled?”
The statement deserves examination, but it does not automatically establish a reporting error.
The meaning of full payment must first be understood.
Full Payment of an Agreed Settlement Amount
A borrower may have paid every rupee required under a compromise settlement agreement.
However, the lender may have accepted less than the amount otherwise due.
In that situation, payment completion and settlement classification may both be accurate.
Full Repayment Without a Compromise
A different situation arises where the borrower states that the entire amount due was repaid without a compromise settlement.
If the report nevertheless reflects Post Write-Off Settled, the reporting classification may require closer examination.
Relevant information may include:
- The lender’s account ledger and repayment records
- Payment receipts and transaction history
- Settlement correspondence, if any
- The nature of any waiver or adjustment
- Closure confirmation and account-status information
- The account’s earlier write-off history
These records help establish whether the reported classification corresponds with the actual sequence of events.
Why Full Repayment Does Not Automatically Erase Historical Information
Even where the borrower establishes that the entire amount due was paid, it does not automatically follow that an accurate historical write-off must be deleted.
The earlier write-off and the subsequent repayment are distinct events.
Whether a particular status should be retained, modified or corrected depends on the verified facts and applicable reporting requirements.
The appropriate objective is accurate reporting of the account’s history—not automatic removal of every adverse classification.
- Can an Incorrect Post Write-Off Settled Status Be Corrected?
Yes. If the reported classification is established to be inaccurate, correction may be appropriate under the applicable credit-information framework.
However, an important distinction must be maintained between an inaccurate account status and an accurate historical classification that the borrower would prefer not to see.
For example, where an account was genuinely written off and subsequently resolved through a compromise settlement, Post Write-Off Settled may accurately describe its history.
The fact that the Current Balance and Amount Overdue have become ₹0 does not, by itself, establish that the classification should be removed.
A different concern arises when the reported information does not correspond with the lender’s verified records.
Potential discrepancies may include:
- A settlement classification that is inconsistent with the actual repayment arrangement.
- An incorrect Current Balance or Amount Overdue.
- Inaccurate account closure or repayment information.
- A mismatch between the reported status and the verified account history.
Credit Rectification should address demonstrable inaccuracies, not automatically eliminate accurately reported historical events.
Why the Exact Reporting Field Matters
A Credit Report may contain separate information concerning account closure, repayment history and written-off or settled status.
Consequently, an account may have a closure date while retaining an accurate historical classification.
A borrower should not assume that the presence of a closure date necessarily requires every other status field to display Closed.
The complete account information must be interpreted together.
- What Are the Responsibilities of the Lender and Credit Bureau?
Credit Institutions and Credit Information Companies perform different functions within India’s credit-information system.
The Reporting Credit Institution
The bank or other reporting Credit Institution furnishes account information to the relevant Credit Information Companies.
It is therefore an important source for verifying:
- The account’s write-off history.
- The nature of the subsequent payment arrangement.
- Whether a compromise settlement occurred.
- The amount presently outstanding.
- The accuracy of the reported account classification.
The Credit Information Company
A Credit Information Company, such as TransUnion CIBIL, maintains credit information received through the applicable reporting framework.
It also provides a mechanism for consumers to raise disputes concerning potentially inaccurate information.
However, lender-furnished information generally requires verification through the concerned Credit Institution before it is modified.
The applicable framework includes the Credit Information Companies (Regulation) Act, 2005, relevant RBI directions and the credit-information correction process.
RBI also prescribes timelines and compensation provisions for qualifying delayed credit-information complaints, subject to the applicable conditions.
A dispute initiates an examination of the information. It does not automatically establish that the information is wrong.
Where a genuine discrepancy is verified, the appropriate correction should reflect the actual account position.
- Does Post Write-Off Settled Mean My Next Loan Will Be Rejected?
Not necessarily.
A lender may consider historical settlement or write-off information when evaluating a new credit application.
However, lending decisions involve several factors.
These may include:
- Income and repayment capacity.
- Existing credit obligations.
- Overall repayment history.
- The amount and type of credit requested.
- Security or collateral, where applicable.
- The lender’s internal credit policy.
A Post Write-Off Settled classification may therefore be relevant to credit assessment, but it does not establish the outcome of every application.
It would be inaccurate to promise loan approval following a status correction.
It would also be inaccurate to claim that every applicant with a settlement-related classification will necessarily be rejected.
The appropriate objective is to ensure that the Credit Report accurately represents the applicant’s credit history.
- When Is Professional Credit Report Assessment Appropriate?
A borrower may require professional examination when the reported status appears inconsistent with the actual payment and closure records.
For example, a borrower may have completed repayment but remain uncertain whether the lender has accurately reported the account’s historical classification.
Another borrower may have entered into a genuine compromise settlement and misunderstand why the account continues to show Post Write-Off Settled.
These situations are not identical.
Professional Credit Report analysis helps distinguish between:
An accurate historical classification: The account was written off and subsequently settled, and the reporting reflects that history.
An inaccurate financial field: The Current Balance or Amount Overdue does not correspond with the verified account position.
A potentially inaccurate classification: The reported status appears inconsistent with the actual write-off, repayment or settlement records.
An incomplete understanding of the account: The borrower has a payment receipt but does not know how the lender classified the underlying transaction.
At Apoorvaa – Credit Bureau Lawyer of India, the focus is on understanding the account-level information before determining whether Credit Rectification is appropriate.
The presence of an adverse status is not, by itself, proof of incorrect reporting.
Equally, the presence of a zero balance does not establish that the complete Credit Report is accurate.
Frequently Asked Questions
- Why does my CIBIL Report show Post Write-Off Settled when the Current Balance is ₹0?
The Current Balance describes the amount presently reported, while Post Write-Off Settled may describe the account’s earlier write-off and subsequent settlement. Both may be accurate at the same time.
- Is Post Write-Off Settled the same as a normal Closed status?
No. The classifications may reflect different account histories. The correct interpretation depends on the underlying repayment and settlement records.
- Does paying the full settlement amount automatically change the status to Closed?
No. Completing a compromise settlement does not automatically mean the account should be reported as an ordinary closure without settlement history.
- What if I paid the entire amount due without a compromise settlement?
The lender’s ledger, payment records, closure documents and earlier write-off history should be examined to determine whether the reported classification is accurate.
- Does every waiver mean the account must be reported as Settled?
No. An ordinary charge reversal or routine payment adjustment is not automatically equivalent to a compromise settlement. The nature of the arrangement matters.
- Can CIBIL remove an accurate Post Write-Off Settled classification simply because I raise a dispute?
No. A dispute is intended to address potentially inaccurate information. It does not guarantee deletion of accurate historical reporting.
- Can this status affect a future loan application?
It may be considered during credit assessment, but the lending decision depends on multiple factors. The classification alone does not determine every application’s outcome.
My Perspective
One of the most common misunderstandings in Credit Report interpretation is the assumption that a zero outstanding balance automatically means the entire account history should appear clean.
The financial position and the historical classification must be examined separately.
A borrower may have completed a payment arrangement and genuinely owe nothing further under that arrangement.
Nevertheless, if the account was previously written off and subsequently resolved through a compromise settlement, that history may remain relevant to its reporting classification.
At the same time, a lender’s classification should not be accepted as accurate without examination where the borrower presents credible records indicating a different repayment history.
The correct question is not simply:
“Have I paid the bank?”
It is:
“Does the Credit Report accurately reflect how the account was written off, repaid, settled or closed?”
That distinction is essential when evaluating a Post Write-Off Settled entry.
Final Takeaway
If your CIBIL Report shows:
Current Balance: ₹0
Amount Overdue: ₹0
Written-off/Settled Status: Post Write-Off Settled
do not automatically conclude that the lender has reported incorrect information.
A zero balance may coexist with an accurate historical settlement classification.
However, if the reported status does not correspond with the verified write-off, repayment and settlement records, the discrepancy may require correction.
Remember:
Zero Balance ≠ Automatic Removal of Historical Status.
Full Payment of a Settlement ≠ Full Repayment Without a Compromise.
An Accurate Historical Classification ≠ An Incorrect Credit Report Entry.
The objective is to establish whether the complete account information accurately represents the underlying credit history.
Professional Credit Report Assessment & Credit Rectification
Have you completed your loan payment but your CIBIL Report still shows Post Write-Off Settled?
Are you unsure whether the classification accurately reflects your repayment and closure records?
Apoorvaa provides professional Credit Report assessment and Credit Rectification services for individuals and businesses where settlement history, account status or other material credit information requires examination.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee removal of accurately reported historical information, an increase in any credit score or approval of a future loan application.
Related Credit Education