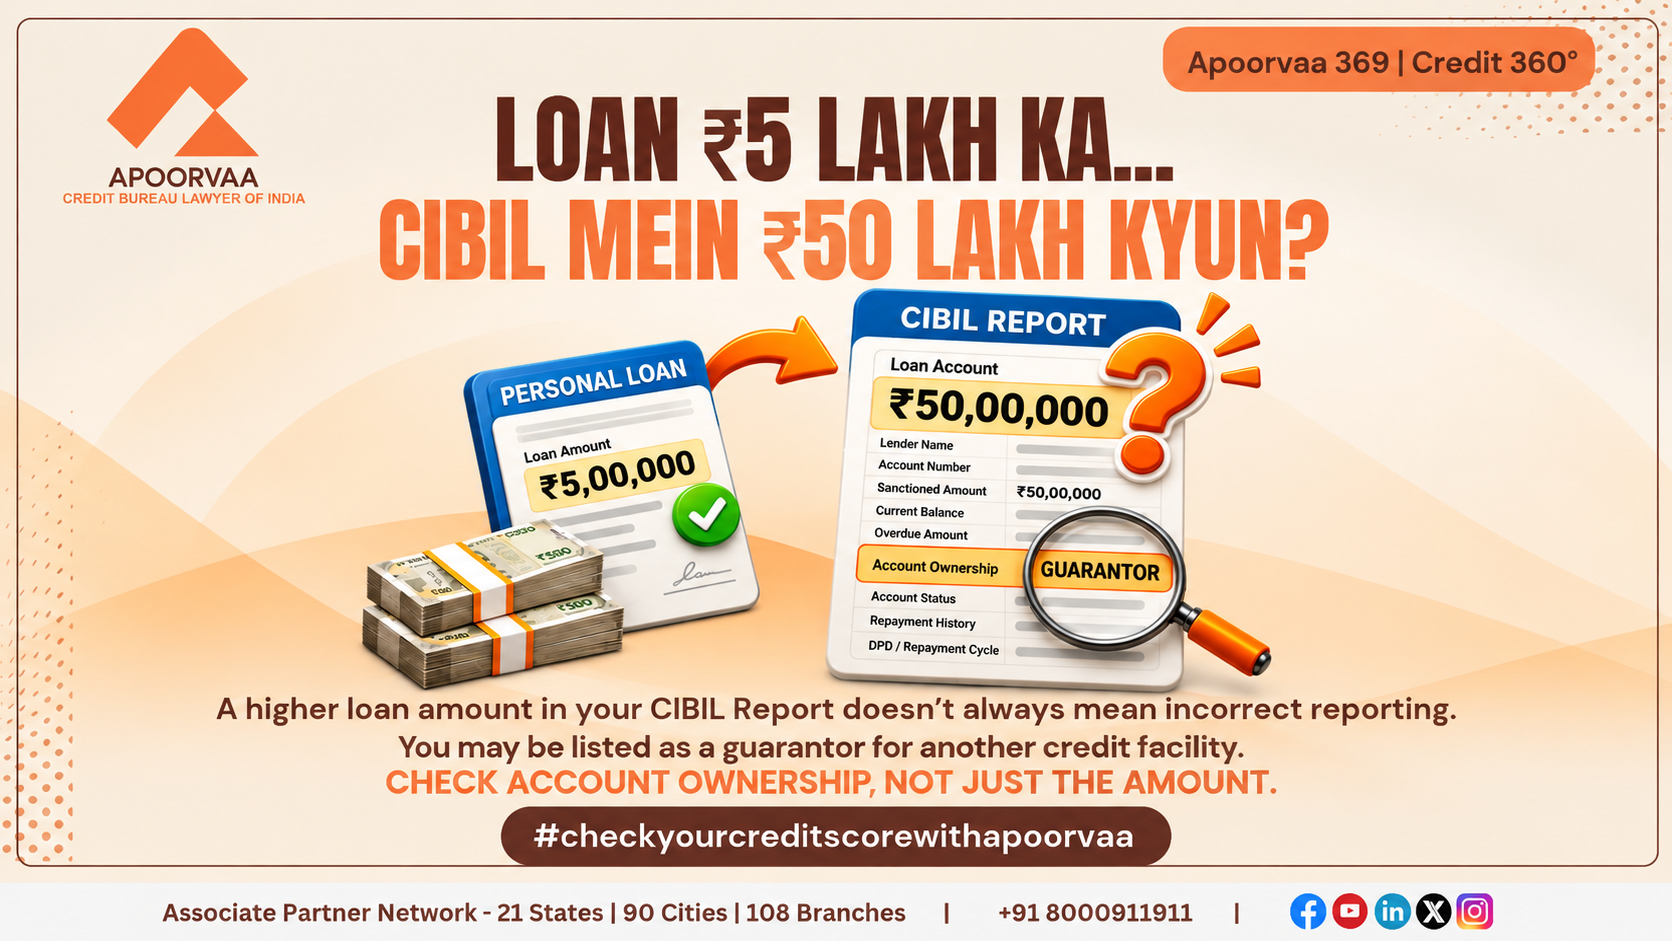
A customer approached Apoorvaa with a concern that appeared straightforward:
“I borrowed only ₹5 lakh, but a ₹50 lakh loan is appearing in my credit information. Why has the bank reported such a large amount?”
At first glance, the difference between ₹5 lakh and ₹50 lakh could suggest an incorrect loan amount.
However, the detailed Credit Report revealed an important distinction.
The customer had personally borrowed ₹5 lakh but had also provided a guarantee for a separate ₹50 lakh credit facility.
The larger amount did not represent an increase in the customer’s personal loan. It related to another account with which the customer was associated as a guarantor.
This case demonstrates why Guarantor Status in CIBIL Report is an essential consideration when examining an apparently unfamiliar or unusually large loan amount.
Credit Report interpretation requires more than comparing the amount remembered by the customer with the amount displayed in a summary.
It requires understanding the underlying credit relationship.
- Why Is a ₹50 Lakh Loan Showing When I Borrowed Only ₹5 Lakh?
A Credit Report can contain information relating to different types of credit relationships.
These may include facilities in which an individual is:
- The primary borrower
- A joint borrower
- A guarantor
A person may therefore be associated with multiple credit facilities without having personally received the proceeds of every facility.
Consider the following illustration:
| Credit relationship | Sanctioned amount | Individual’s role |
| Personal loan | ₹5,00,000 | Primary borrower |
| Separate credit facility | ₹50,00,000 | Guarantor |
The two entries describe different credit relationships.
The presence of the ₹50 lakh account does not, by itself, establish that the ₹5 lakh personal loan has been inflated.
Equally, it does not establish that the customer currently owes ₹50 lakh.
The relevant enquiry is whether the reported facility is genuinely associated with the individual and whether the reported account details accurately reflect that relationship.
Why an Account Summary May Be Misunderstood
A customer may first encounter an unexpected amount through a loan summary, lending application or other credit-information display.
Such a display may not provide all the information needed to interpret the account correctly.
Different summaries can present different levels of detail.
A full Credit Report may provide additional context concerning account ownership, lender identity, sanctioned amount, reported balance, overdue and repayment performance.
Consequently, an apparent amount discrepancy should not automatically be classified as incorrect lender reporting.
The amount is only one field. The ownership relationship gives that amount its meaning.
- Can a Guarantor’s Loan Appear in a CIBIL Report?
Yes.
A guarantee can create a credit relationship that is relevant to the guarantor’s credit information.
TransUnion CIBIL’s published consumer guidance specifically recognises that loans for which an individual acts as guarantor may appear in their Credit Report.
It also explains that repayment defaults by the principal borrower can affect the guarantor’s credit profile.
This reflects an important principle: a guarantee is not merely an informal introduction between a borrower and a lender.
It can create a substantive financial obligation.
Why Guarantee Reporting Is Different from Incorrect Loan Ownership
Suppose a person guarantees a business loan of ₹50 lakh.
The individual may never have received the sanctioned funds in their personal bank account.
Nevertheless, the guarantee may be a genuine obligation associated with that individual.
If the Credit Report correctly identifies that relationship, the mere presence of the ₹50 lakh facility is not sufficient grounds to call it an ownership error.
A different issue arises if:
- The individual never provided the reported guarantee.
- The facility is attributed to the wrong person.
- The account is incorrectly classified as personal borrowing.
- Material financial or account-status information is inaccurate.
These situations require different interpretations.
A genuine guarantee should not be confused with an incorrectly attributed loan.
- Borrower vs Joint Borrower vs Guarantor: Why Ownership Classification Matters
Account ownership is a fundamental part of professional Credit Report analysis.
Although borrowers, joint borrowers and guarantors may all be associated with credit obligations, their contractual relationships are not identical.
Primary Borrower
A primary borrower obtains a credit facility and undertakes repayment obligations under the relevant loan arrangement.
For example, the customer’s ₹5 lakh personal loan represents their direct borrowing relationship.
Joint Borrower
A joint borrower participates in the borrowing arrangement alongside another borrower.
The specific obligations of each joint borrower depend on the loan agreement and applicable legal provisions.
A joint borrower should not automatically be classified as a guarantor simply because another person is also associated with the facility.
Guarantor
A guarantor provides a guarantee in respect of another person’s or entity’s obligation.
Under Section 126 of the Indian Contract Act, 1872, a contract of guarantee concerns an undertaking to perform a promise or discharge another person’s liability in the event of default.
Section 128 provides the general rule that the surety’s liability is co-extensive with that of the principal debtor unless the contract provides otherwise.
The precise scope of liability therefore requires consideration of the guarantee terms and applicable law.
From a Credit Report perspective, this distinction is critical.
A person may be legally associated with a ₹50 lakh facility without being its primary borrower.
At the same time, the guarantee should not be dismissed as having no legal or credit implications.
Why an Incorrect Ownership Classification Matters
Imagine that the customer genuinely guaranteed a ₹50 lakh loan, but the reported ownership information appears to identify the customer as the primary borrower.
That is not the same issue as a completely unknown loan.
The underlying guarantee may be genuine, while the ownership classification may require verification.
Professional examination should distinguish between:
Existence of the account: Is the credit facility genuine?
Association with the individual: Is the person correctly linked to that facility?
Nature of the association: Is the person a borrower, joint borrower or guarantor?
Accuracy of the reported information: Do the financial and status fields reflect the verified account position?
A discrepancy in one field does not automatically establish that every other field is incorrect.
- Sanctioned Amount vs Current Balance vs Amount Overdue
One of the most common reasons for misunderstanding a Credit Report is treating every monetary field as though it represents the same liability.
In reality, the fields describe different aspects of an account.
Sanctioned Amount
The sanctioned amount generally represents the credit amount approved under the facility.
In the customer example, ₹50 lakh was the sanctioned amount associated with the guaranteed facility.
It did not automatically mean that the customer personally received ₹50 lakh.
Current Balance
The Current Balance represents the balance reported against the account at the relevant reporting date.
It may differ substantially from the original sanctioned amount.
The interpretation must also account for the nature of the credit facility and the reporting context.
Amount Overdue
The Amount Overdue identifies the amount reported as overdue.
A ₹50 lakh sanctioned facility may have a substantially different reported overdue amount—or no overdue amount at the relevant reporting date.
The sanctioned amount should therefore never be presented as though it is automatically the amount overdue.
Account Status
Account status provides another layer of information.
Depending on the account and reporting circumstances, the report may reflect an active, closed, settled, written-off or other applicable status.
A large sanctioned amount and an adverse account status are not interchangeable concepts.
Repayment History
Repayment history provides information about payment performance over the periods reflected in the report.
For a guarantor, repayment problems involving the underlying facility can have implications for the credit profile.
However, the repayment history must still be interpreted in relation to the actual facility and the individual’s reported role.
An Illustrative Comparison
| Credit Report field | Example | What it tells us |
| Sanctioned Amount | ₹50,00,000 | Size of the sanctioned facility |
| Current Balance | ₹32,00,000 | Illustrative reported balance |
| Amount Overdue | ₹0 | Illustrative overdue position |
| Ownership | Guarantor | Individual’s reported relationship |
| Account Status | Active | Illustrative reported status |
These figures are hypothetical and are not the actual financial details of the customer case.
The illustration demonstrates why the presence of a ₹50 lakh sanctioned amount does not automatically establish a ₹50 lakh overdue liability.
The complete account information must be considered.
- Why Lender Name, Account Details and Dates Must Be Examined Together
Account ownership cannot always be interpreted reliably from the sanctioned amount alone.
The lender name, account identifier, date opened, loan type and reported ownership classification provide context.
For example, a customer may recognise the bank associated with their ₹5 lakh personal loan but overlook a separate facility guaranteed through another lender.
Alternatively, the customer may recognise the ₹50 lakh facility only after the underlying borrowing relationship is identified.
The objective is to understand whether the reported account corresponds with a genuine credit relationship.
Why Dates Matter
Dates can help distinguish one facility from another and place the account within its reporting history.
However, an account’s date opened or reporting date should not be interpreted independently of its ownership and financial information.
Similarly, the presence of two different sanctioned amounts does not necessarily indicate that one account has replaced another.
In our customer case, understanding the guarantor relationship changed the interpretation of the ₹50 lakh entry.
The key finding was not simply that the amount was large.
It was that the customer had a different role in the larger facility.
That is the distinction professional Credit Report analysis must establish before any rectification conclusion is reached.
- When Is Guarantor Reporting Correct, and When Could It Be an Error?
The central question in our ₹5 lakh versus ₹50 lakh customer case was not whether the customer personally received ₹50 lakh.
It was whether the customer had a genuine credit relationship with that facility.
A guarantee may legitimately appear in a Credit Report. However, its presence does not automatically establish that every associated detail has been reported correctly.
Consider three distinct situations.
Situation A: A Genuine Guarantee Is Correctly Reported
The individual provided a guarantee for the ₹50 lakh facility, and the reported information accurately reflects that relationship.
In this situation, the account’s appearance is not automatically an error.
The fact that the individual personally borrowed only ₹5 lakh does not invalidate a separate, genuine guarantee.
Situation B: A Genuine Guarantee Is Incorrectly Classified
The individual provided a guarantee, but the report appears to identify them as the primary borrower.
Here, the underlying credit relationship may be genuine while the ownership classification requires examination.
The appropriate question is whether the reported ownership accurately corresponds with the relevant loan and guarantee documentation.
Situation C: The Guarantee Was Never Provided
The individual neither borrowed nor guaranteed the reported facility.
This raises a materially different concern involving possible incorrect account attribution.
If verification establishes that the account has been associated with the wrong individual, correction may be warranted.
Professional Credit Rectification begins by distinguishing these situations—not by treating every unexpected amount as an incorrect loan.
- Can a Genuine Guarantee Be Removed from a Credit Report?
A person cannot assume that a genuine guarantee must be deleted merely because they did not personally receive the loan proceeds.
A guarantee can create enforceable obligations under the applicable law and contractual terms. It may also have credit-reporting implications.
However, there is an important distinction between removing an accurately reported credit relationship and correcting inaccurate information within that relationship.
For example, a genuine guarantee may still require examination if the reported ownership, balance, overdue, account status or other material information is inconsistent with the verified records.
Similarly, the subsequent closure or discharge of a guarantee does not necessarily mean that all historical information must disappear immediately. The applicable reporting and retention requirements must be considered.
The correct objective is accurate credit information, not the automatic deletion of an unfavourable account.
- How Does the Credit Information Correction Framework Apply?
Where credit information appears inaccurate, the relevant Credit Institution and Credit Information Company have roles under India’s credit-information framework.
The Credit Information Companies (Regulation) Act, 2005 and the applicable RBI directions provide the broader regulatory structure.
The lender or other reporting Credit Institution is important because it furnishes the underlying account information.
A Credit Information Company, such as TransUnion CIBIL, maintains and provides credit information received through the reporting framework.
Where an account’s ownership or other information is disputed, the relevant reporting institution’s verification is generally necessary.
RBI’s framework also provides timelines and compensation provisions for qualifying delayed credit-information complaints, subject to the applicable conditions.
However, a complaint does not automatically establish that the disputed information is incorrect.
For a guarantor-related discrepancy, the key issue remains whether the reported information accurately represents the individual’s actual credit relationship.
- Why Professional Credit Report Analysis Matters
A Credit Report may contain multiple facilities, different ownership relationships and several financial fields.
An isolated amount cannot reliably explain all of them.
In the customer case discussed here, the initial concern was that a ₹50 lakh loan appeared despite the customer’s personal borrowing being ₹5 lakh.
The detailed examination identified the customer’s guarantor relationship with the larger facility.
That finding changed the nature of the enquiry.
Rather than assuming the bank had inflated the personal loan amount, the relevant consideration became whether the guarantee and its associated account information were correctly reported.
Professional analysis can help distinguish:
- Genuine personal borrowing
- Genuine joint borrowing
- Genuine guarantor relationships
- Incorrect ownership classification
- Incorrect account attribution
- Material discrepancies in balances, overdue, status or repayment information
These distinctions matter because different reporting concerns may require different forms of verification.
At Apoorvaa, our approach is centred on understanding the account-level information before determining whether a matter involves Credit Rectification.
The presence of a large loan amount is a reason to examine the report carefully.
It is not, by itself, proof of a reporting error.
Frequently Asked Questions
Can a ₹50 lakh guaranteed loan appear alongside my ₹5 lakh personal loan?
Yes. A Credit Report may contain information about both your direct borrowing and a separate facility for which you provided a guarantee.
Does a ₹50 lakh sanctioned amount mean ₹50 lakh is overdue?
No. Sanctioned Amount, Current Balance and Amount Overdue are different fields. The actual reported figures and account circumstances must be examined.
Can a guarantor’s credit profile be affected by repayment problems?
Yes. A guarantee can have credit implications, including where the underlying borrower defaults. The guarantee terms and applicable law determine the guarantor’s legal obligations.
What if I genuinely guaranteed the loan but my ownership is shown incorrectly?
The reported ownership classification should be examined against the actual credit relationship and relevant documentation. A material inaccuracy may require correction.
What if I never provided the reported guarantee?
An unfamiliar guarantee should be examined to establish whether the account has been incorrectly attributed to you. Where inaccurate reporting is verified, the applicable correction mechanism may be relevant.
Can Apoorvaa guarantee removal of a guarantor account?
No. The appropriate outcome depends on the verified facts and applicable reporting requirements. An accurately reported guarantee cannot be treated as removable merely because the guarantor did not receive the loan proceeds.
My Perspective
A customer seeing ₹50 lakh in their Credit Report after personally borrowing only ₹5 lakh has every reason to seek an explanation.
But the explanation must come from the complete account information—not from the difference between the two amounts alone.
Our customer case demonstrates the importance of distinguishing direct borrowing from a genuine guarantee.
A guarantor may be associated with a substantial credit facility without having received the loan proceeds personally.
At the same time, that association must be accurately represented in the Credit Report.
In my view, the most important principle is this:
Before questioning the amount, establish the ownership relationship. Before seeking rectification, establish the reporting discrepancy.
This approach helps distinguish genuine credit obligations from information that may require correction.
Final Takeaway
If your personal loan is ₹5 lakh but your CIBIL Report shows a ₹50 lakh facility, do not immediately conclude that the lender has reported an inflated loan.
You may be associated with a separate facility as a guarantor.
A ₹50 lakh sanctioned amount does not automatically mean you personally borrowed ₹50 lakh, that ₹50 lakh remains outstanding or that ₹50 lakh is overdue.
The correct interpretation depends on the complete account information, particularly the ownership classification.
A genuine guarantee should be recognised. An inaccurate credit entry should be examined for rectification.
Both conclusions require proper verification.
Professional Credit Report Assessment & Credit Rectification
Does your Credit Report contain a loan amount you do not recognise?
Are you uncertain whether an account reflects your personal borrowing, joint borrowing or a guarantee?
Apoorvaa provides professional Credit Report assessment and Credit Rectification services for individuals and businesses where account ownership, guarantor status or other material credit information requires examination.
📞 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Credit Rectification does not guarantee deletion of accurately reported information, an increase in any credit score or future loan approval.
Related Credit Education