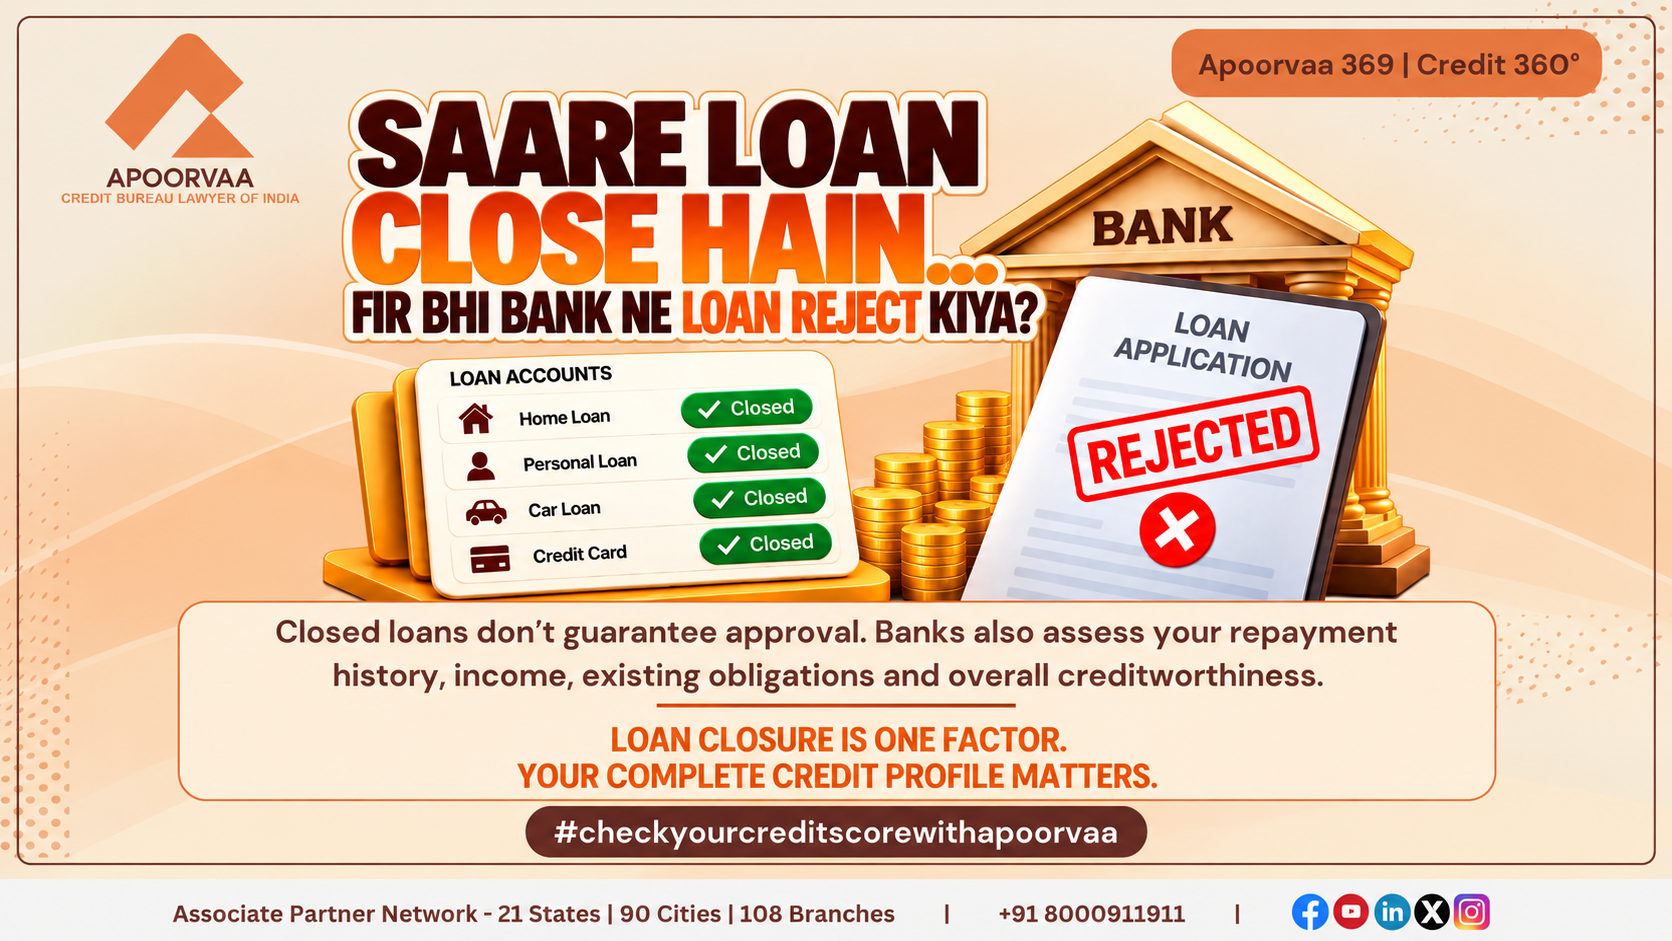
“All my loans are closed, so why is the bank still rejecting my loan application?”
This question arises when a borrower has successfully repaid previous credit facilities but faces rejection while applying for a new loan.
The borrower may have no active personal loan, home loan, vehicle loan or business loan. Every account may be marked as closed, and the current outstanding balances may be zero.
Yet the new application is declined.
The misunderstanding is the assumption that having no active loans automatically establishes creditworthiness or guarantees eligibility for fresh credit.
In reality, a lender may examine historical repayment behaviour, account classifications, financial capacity and its own underwriting requirements.
A CIBIL Report contains more than a list of currently active loans. It may also contain information about how previously closed accounts were managed.
Understanding that distinction is essential when all loans are closed but a loan is rejected.
- Why Is My Loan Rejected When All My Loans Are Closed?
Loan closure confirms an account’s reported status. It does not independently establish that the borrower satisfied every repayment obligation on its original due date.
Consider two borrowers who have closed all previous loans.
| Credit Profile | Borrower A | Borrower B |
| Active Loans | None | None |
| Current Outstanding | ₹0 | ₹0 |
| Historical EMI Payments | Generally regular | Several delayed payments |
| Previous Overdue Reporting | No reported overdue history | Past overdue amounts subsequently cleared |
| Current Loan Status | Closed | Closed |
Both borrowers have zero current outstanding debt.
However, their historical repayment records differ.
A lender may consider this difference while assessing a new application.
For Borrower B, the bank may examine the severity, frequency and recency of earlier repayment irregularities.
That does not mean Borrower B will necessarily be rejected by every lender. Lending decisions depend on multiple factors, and institutions may apply different eligibility policies.
Closed accounts and satisfactory historical repayment behaviour are related, but they are not interchangeable.
- Does a Closed Loan Still Appear in a CIBIL Report?
Yes.
A loan that has been fully repaid and closed may remain visible in the borrower’s CIBIL Report as part of historical credit information.
The report may contain details such as:
- Credit facility type and account information.
- Reported account opening and closure dates.
- Historical repayment information.
- Current and previously reported outstanding amounts.
- Account status and relevant classifications.
This historical information can help lenders assess how credit obligations were managed over time.
Closed Does Not Mean Deleted
A borrower may assume that a closed account should disappear from the credit report.
However, the continued presence of accurate historical account information is not automatically an error.
For example, a personal loan closed last year may remain visible with its historical repayment record.
The important distinction is between the current legal and financial position of the account and its historical credit-reporting information.
A loan may no longer have any amount outstanding while still retaining a record of previous repayment behaviour.
- Can Historical EMI Delays Affect a New Loan Application?
Potentially, yes.
Suppose a borrower had a personal loan with a monthly EMI of ₹25,000.
During the repayment period, three instalments were delayed because of temporary financial difficulties.
The borrower later paid the overdue amounts, completed the remaining EMIs and closed the loan.
At the time of the new loan application:
- The personal loan is closed.
- The current outstanding balance is zero.
- Earlier repayment delays may remain in the reported payment history.
The borrower has completed the financial obligation, but that does not necessarily make the historical repayment record equivalent to a record where every EMI was paid on time.
Why Recency and Severity Matter
Lenders may assess repayment irregularities differently depending on their policies.
A recent missed payment may be evaluated differently from an older, isolated delay.
Similarly, a significant period of overdue reporting may receive different consideration from a minor repayment irregularity.
The same general concern may arise with business credit facilities, including working-capital accounts where interest or other payment obligations were not met according to agreed terms.
However, the presence of historical repayment delays does not automatically result in rejection by every bank.
Credit history is one input into a broader lending decision.
- Closed Account vs Clean Repayment History: The Critical Difference
The expressions closed account, zero outstanding and clean repayment history describe different aspects of a credit profile.
| Credit-report information | What it generally indicates |
| Account Closed | The lender has reported the account as closed |
| Current Balance ₹0 | No current outstanding balance is reported |
| Historical Payment Record | How repayments were reported during the account’s life |
| Settled Classification | An agreed settlement arrangement, which may differ from full contractual repayment |
| Written-off Classification | A lender’s accounting or credit classification that does not, by itself, establish that the debt was waived |
A borrower may have an account showing both Closed and a zero current balance while historical repayment irregularities remain visible.
This is not necessarily contradictory.
Full Repayment, Settlement and Write-off
These terms should not be treated as equivalent.
Full Repayment: The borrower has satisfied the applicable repayment obligation.
Settlement: The lender has accepted an agreed resolution that may involve payment of less than the full amount otherwise payable.
Write-off: An accounting treatment or classification by the lender that does not automatically eliminate the borrower’s legal repayment obligation.
These distinctions may matter when a lender reviews historical account information.
Where the credit report inaccurately represents the account’s actual status or repayment outcome, verification may be appropriate.
However, accurate adverse information cannot simply be deleted because the borrower has subsequently repaid the debt.
Credit Rectification concerns genuine reporting inaccuracies, not the removal of legitimate credit history.
- Does Zero Outstanding Mean a Borrower Is Eligible for a New Loan?
No.
Zero outstanding is relevant to a borrower’s current debt position, but it does not establish eligibility for a new loan.
Consider a borrower who has closed every previous loan and currently owes nothing to any lender.
The borrower now applies for a ₹30 lakh loan.
Even if the historical credit report is satisfactory, the bank may still assess:
- Whether the borrower’s verified income supports the proposed repayment.
- Whether bank statements demonstrate sufficient cash flow.
- Whether existing financial commitments affect repayment capacity.
- Whether employment or business income is sufficiently stable.
- Whether the application meets the lender’s product-specific criteria.
Income tax returns and other financial documents may also be relevant, depending on the loan type.
Some lenders may conduct additional verification or a personal discussion, but these procedures are not universal.
The important distinction is that credit-report information and lender underwriting eligibility serve different purposes.
A CIBIL Report provides credit information. It does not independently determine whether the borrower qualifies for the requested loan.
Even a borrower with no active loans and an otherwise satisfactory repayment history may fail to meet a particular lender’s eligibility requirements.
- What Else Do Banks Check Before Approving a Loan?
When all loans are closed but a new loan is rejected, the reason may extend beyond the borrower’s CIBIL Report.
Banks and financial institutions assess credit applications according to their own underwriting policies.
Depending on the loan product, the assessment may include:
Income and Repayment Capacity: Whether verified earnings are sufficient to support the proposed EMI.
Bank Statements and Cash Flow: Whether financial transactions demonstrate the capacity to meet repayment obligations.
Income Tax Returns: Income and financial information, where applicable.
Employment or Business Stability: The reliability and continuity of the applicant’s income.
Existing Financial Obligations: Other commitments that may affect repayment capacity.
Historical Credit Behaviour: Previously reported repayment delays, overdue amounts and relevant account classifications.
Some lenders may also conduct field investigations, business verification or a personal discussion with the applicant.
These procedures are not identical across all lenders or loan products.
Importantly, even a borrower with an accurate credit report and satisfactory repayment history is not guaranteed loan approval.
The final lending decision remains with the lender.
- Can Incorrect Information in Closed Accounts Affect Loan Assessment?
Yes. A closed loan may contain information that requires verification.
For example, a borrower may have fully repaid a personal loan, but the CIBIL Report may still show an incorrect outstanding amount or an account classification inconsistent with the lender’s records.
Such information could be relevant when a lender evaluates the application.
However, two situations must be distinguished.
Genuine Credit-Reporting Inaccuracy
The reported information does not accurately reflect the account’s actual position or the lender’s records.
This may require investigation and correction.
Legitimate Historical Repayment Information
The borrower genuinely delayed certain EMIs, subsequently cleared the overdue amount and eventually closed the loan.
The earlier delays may remain part of the historical repayment record.
Their presence does not automatically indicate incorrect reporting.
Under RBI’s credit-information framework, credit institutions and credit information companies have responsibilities concerning accurate credit-information reporting and correction of inaccuracies.
However, the framework does not mean that legitimate historical repayment information must be removed simply because the account is now closed.
Credit Rectification should address inaccurate information, not erase accurate repayment history.
- Why Reviewing Your Complete Credit Report Matters Before Applying
Before applying for a major loan, understanding the complete credit report can help identify concerns that may otherwise be overlooked.
A professional Credit Report analysis may examine:
- Historical repayment information in closed accounts.
- Outstanding balances and account classifications.
- Potential inconsistencies between reported information and lender records.
- Relevant changes across the borrower’s credit profile.
- Whether a specific discrepancy warrants further verification or Credit Rectification.
Such an assessment can provide clarity about reported credit information.
However, professional Credit Report analysis cannot determine or guarantee that a bank will approve a loan.
Lender eligibility involves additional financial and underwriting considerations.
At Apoorvaa – Credit Bureau Lawyer of India, our professional analysis focuses on account-level reporting accuracy, historical credit information and genuine Credit Rectification requirements.
The purpose is to support informed credit decisions—not promise a particular lending outcome.
Frequently Asked Questions
- Can a bank reject my application even if all my loans are closed?
Yes. Historical repayment behaviour, income, repayment capacity and lender-specific eligibility requirements may all influence the decision.
- Does zero outstanding mean my CIBIL Report has no negative history?
No. A zero current balance does not automatically eliminate previously reported repayment delays or other historical account information.
- Can old EMI delays remain visible after loan closure?
Yes. Accurately reported repayment history may remain visible after the account is closed.
- Can a genuinely incorrect closed-account entry be corrected?
Yes. An identifiable reporting inaccuracy may be examined through the applicable verification and correction process.
- Can Credit Report analysis guarantee loan approval?
No. It can help identify potential credit-report concerns, but the lender independently determines eligibility and approval.
My Perspective
As a professional working in credit-bureau law and Credit Rectification, I believe borrowers should understand the difference between completing a financial obligation and satisfying a lender’s requirements for a new loan.
A closed account reflects the reported status of a credit facility.
Historical repayment information reflects how that facility was managed.
Loan eligibility involves a further assessment of financial capacity, credit history and the lender’s underwriting policy.
These are related considerations, but they are not interchangeable.
Before applying for a major loan, understanding the complete credit report can help identify genuine reporting discrepancies and provide a clearer picture of historical credit behaviour.
Final Takeaway
Having all your loans closed is a positive financial position, but it does not automatically establish a flawless repayment history or guarantee approval for fresh credit.
A lender may review historical EMI delays, account classifications, income, repayment capacity and other eligibility requirements.
ALL LOANS CLOSED ≠ GUARANTEED LOAN APPROVAL
ZERO OUTSTANDING ≠ CLEAN REPAYMENT HISTORY
UNDERSTAND YOUR COMPLETE CREDIT REPORT BEFORE APPLYING FOR A NEW LOAN.
All Loans Closed but Facing Loan Rejection?
If your previous loans are closed but you are concerned about historical credit information or possible reporting inaccuracies, Apoorvaa provides professional Credit Report analysis.
Our services focus on evaluating account-level information, identifying genuine discrepancies and assessing whether Credit Rectification is appropriate.
Purchase your Credit Report and get it professionally analysed by Apoorvaa.
Call: 8000 911 911
Apoorvaa – Credit Bureau Lawyer of India
Professional Credit Report analysis and Credit Rectification do not guarantee loan eligibility, loan approval or a particular credit score.
Related Credit Education